The Morning Bull – US Market Morning Update Friday, Nov, 20 2026
US stocks look set to open weaker, with S&P 500 and Nasdaq futures in the red as investors refocus on the Federal Reserve. The dominant driver is a renewed push toward higher US rates after hawkish Fed minutes.
Minutes from the October meeting showed most Fed officials leaning toward additional tightening, and markets now price roughly a 25bp hike next month with a smaller possibility of 50bp. The US 10 year yield sits near 5.05% after a four session slide, while the dollar index is pushing toward 104, reflecting that higher rate expectation.
Higher policy expectations keep borrowing costs elevated for households and companies, which can pressure capital spending plans and squeeze interest sensitive business models. A stronger dollar also tightens financial conditions by making US exports less competitive and compressing overseas earnings when they are translated back into US$.
The open question is how long the Fed can lean hawkish without triggering a sharper growth scare. Today’s focus is on upcoming Fed speeches, which could either reinforce the case for another hike or hint at more patience instead.
Stocks to Watch Before the Opening Bell
Merck (MRK)
Fresh data from Merck’s Phase 3 TroFuse-015 trial is front and center. Its drug sacituzumab tirumotecan met the primary goal of improving overall survival in heavily pretreated gastroesophageal adenocarcinoma. The therapy is a TROP2-directed antibody drug conjugate with a safety profile in line with earlier work. Investors now watch for regulatory filings and how Merck positions this within its oncology lineup.
General Dynamics (GD)
General Dynamics is juggling wins and setbacks in government contracting. The group secured a US Army deal worth up to US$333m over five years for Stryker vehicle sustainment, plus a place in a US$7.13b Navy electronic warfare program shared among 28 contractors. At the same time, it lost a challenge over a separate US$10.5b Special Operations logistics award to Lockheed Martin.
Anthropic PBC (ANT)
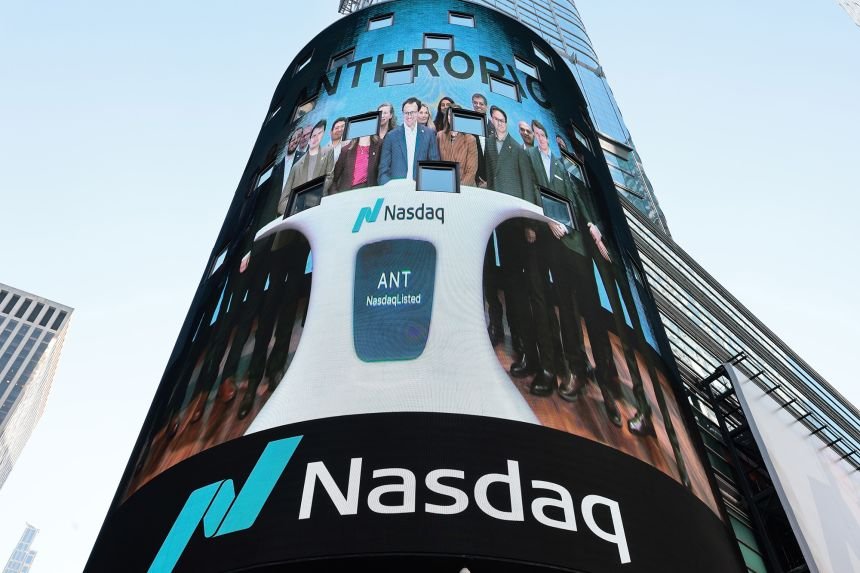
Anthropic PBC is in focus after Purpose Investments launched the Purpose Anthropic Yield Shares ETF in Canada. The product uses a covered call approach that targets monthly income while keeping exposure to Anthropic. The ETF gives investors another route into the AI theme without buying single equity directly. Attention now turns to trading volumes and how closely the fund tracks the underlying shares.
Top Movers
- Insmed (INSM) jumped 20.58% after reports that Sanofi is exploring a potential takeover of the biotech group.
- PDD Holdings (PDD) advanced 11.04% as Q3 earnings beat expectations and multiple broker upgrades followed the profit surprise.
- Palo Alto Networks (PANW) gained 6.42% following a strong Q1 beat, raised FY2027 guidance and a US$4.5b Applied Compute acquisition.
Top Losers
- Williams-Sonoma (WSM) fell 15.16% after Q3 earnings beat, as analysts cut price targets following high expectations and softer comps.
- Zoom Communications (ZM) declined 9.56%.
- Nebius Group (NBIS) declined 9.39% as neocloud and AI stocks extended a selloff on funding and demand concerns.

On The Radar
US traders head into the next few sessions with Fed messaging, inflation gauges and a heavy tech and retail earnings slate doing most of the work on rate expectations and sector positioning.
- Fed Waller speech, Fri 20 Nov. Any push for more tightening after the October minutes already flagged a possible 25bp move would keep pressure on rate sensitive areas like housing and utilities and support the stronger dollar story.
- Michigan Consumer Sentiment Final, Fri 20 Nov. A reading above the 51.5 consensus would point to a firmer US consumer than the prior 48.0 print suggested and help support discretionary stocks into the holiday period, while a softer figure would do the opposite.
- Best Buy, Tue 24 Nov. Q3 2027 numbers put the spotlight on comparable sales and gross margin in core electronics, which shows how higher financing costs and promotional activity are feeding through to big ticket spending.
- Dell Technologies, Tue 24 Nov. Q3 2027 results will hinge on infrastructure and PC revenue and on margin commentary that shows how the group is handling component costs and a firm US dollar in its global orders.
- Core PCE Price Index MoM, Wed 25 Nov. An October reading above the 0.3% forecast would reinforce the case for more Fed tightening and support higher Treasury yields, while a softer print would ease some pressure across growth stocks.
Sector & Industry Watch
Tech: Fed nerves hit high-growth stories
Tech has retreated over the past week, with a weaker 7 day return than the broader US Market after the Fed minutes pushed rate expectations higher and lifted the dollar. AI headlines around Anthropic, Microsoft and others have not offset that drag, since higher borrowing costs reduce what investors are willing to pay for future profits from cloud, software and data centers.
If you hold broad tech ETFs, the clearest near term swing factor is today’s Fed Waller speech. Any firm push for more tightening would keep pressure on valuations, even if AI earnings commentary stays upbeat.
Semiconductors: AI chips squeezed by policy worries
Semiconductors are having a tougher week than Tech overall, with the 7 day return weaker again as export control stories, the AMD short seller report and talk around Nvidia’s China exposure all weigh on sentiment. Strong news like Intel’s chip breakthrough and new AI related wins at Teradyne and Microchip sits alongside concern about tighter rules on advanced processors headed to Chinese firms.
For anyone in chip ETFs or AI hardware stocks, the single catalyst to watch is Washington’s next move on export controls to China. A stricter framework would matter for revenue mix at several US chipmakers and could keep this industry more volatile than broader Tech.
Energy & Oil and Gas: Softer crude after strong 12 month run
Energy and Oil and Gas are down over the past 7 days and 30 days even though both sectors still show gains of roughly 32% to 33% over 12 months. Crude holding near a three month low after a US inventory build is feeding into that short term pullback, while deals at TechnipFMC and Cheniere underline how producers keep investing carefully when pricing cools.
If your portfolio includes US producers or LNG linked stocks, weekly US petroleum inventory data is the key dial now. Bigger builds can keep questions alive about demand and leave Energy lagging rate sensitive areas like Tech and Real Estate.
Metals and Mining: Copper and rare earth stories under pressure
Metals and Mining is one of the weakest groups this week, with the sector’s 7 day return down about 12.4% and slightly negative year to date despite a positive 1 year figure. News around Freeport McMoRan’s Indonesia operations, new US rare earth processing plans and antimony supply efforts shows plenty happening on the ground, yet the stronger dollar and recent copper price drop are still weighing on listed miners.
If you hold diversified mining or copper focused ETFs, the variable to track is the US dollar trend. A firm dollar can keep pressure on commodity sectors even when individual project updates, such as new US copper finds, look constructive.
Healthcare & Pharmaceuticals & Biotech: Drug pipelines vs short term swings
Healthcare and Pharmaceuticals & Biotech have both eased over the last 7 days, while their 12 month returns still sit ahead of the US Market helped by strong past earnings and active pipelines. Fresh trial and approval news from Merck, Regeneron, Bristol Myers Squibb and others keeps attention on product data rather than day to day macro headlines.
If you rely on Healthcare as a steadier part of your portfolio, the main US catalyst in view is today’s Michigan Consumer Sentiment reading. A weaker consumer backdrop can keep interest in sectors with more predictable cash flows, which often includes large pharma alongside Consumer Staples and Utilities.
Don’t Wait For The Winners, Find Them
With Fed officials leaning toward more tightening and the 10 year yield near 5.05%, many investors are rethinking risk and starting with this list of 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com