Updated Output Guidance Change The Bull Case For BP Stock (LSE:BP.)?

  • BP updated its third quarter 2026 production guidance, now expecting reported upstream output of 2,190 mboe/d to 2,240 mboe/d, split between Oil production & operations of 1,415 mboe/d to 1,445 mboe/d and Gas & low carbon energy of 775 mboe/d to 795 mboe/d.

  • The more granular breakdown between oil operations and gas and low carbon energy gives investors a clearer view of BP’s near term operating mix and focus.

  • We will now examine how BP’s more specific upstream production guidance might influence the broader investment narrative around its execution.

Compare BP’s updated oil and gas mix with other energy players by scanning our hand-picked list of 4 resilient stocks with low risk scores positioned for steadier returns in volatile commodity cycles.

BP Investment Narrative Recap

To own BP, an investor needs to believe management can keep turning a large, complex upstream portfolio into steadier cash generation while gradually reshaping the mix toward gas and lower carbon assets. The higher, more detailed Q3 2026 production guidance speaks to execution on near term volumes, but does not fundamentally change the long running story around project quality and capital discipline.

The bigger swing factor in the short term is still how efficiently BP converts those barrels into earnings and free cash flow, given prior one off items and impairments. The main risk remains capital misallocation between traditional oil and new energy projects, where past write downs in hydrogen and biofuels underline how easily returns can disappoint.

The Jio bp and Kia India charging tie up is the disclosure that lines up best with the current focus on BP’s gas and low carbon segment in the production guidance. While the near term impact on reported mboe/d is limited, the deal gives the company a clearer operational beachhead in EV charging infrastructure across more than 23,500 accessible points.

For you as a shareholder, that matters because it shows the low carbon and customer facing parts of BP are not just a slide in the deck but are moving into real network build out, alongside the heavy upstream program. Execution risk stays high after prior low carbon impairments, so progress on utilisation, returns on these charging assets, and cash generation will be key catalysts to watch next to core upstream delivery.

BP’s current analyst narrative points to revenues of US$197.0b and earnings of US$10.1b by 2029, based on an assumed yearly revenue decline of 2.9%. That implies earnings rising by about US$4.7b from US$5.4b today to reach the 2029 consensus level.

Uncover why BP’s fair value indicates a 4% potential upside to its current price before the market closes that gap.

LSE:BP. 1-Year Stock Price Chart

Exploring Other Perspectives

Some of the most optimistic analysts lean into BP’s new production detail as a possible validation of their volume stability story. Before this guidance, they were already pencilling in revenue of about US$237.5b and earnings of US$12.3b by 2029. That is far above the US$197.0b and US$10.1b consensus view, so you should expect opinions to move as fresh data lands.

Explore 4 other BP fair value estimates, including one that suggests potential upside of as much as 67% from the current price.

Reach Your Own Conclusion

Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.

Looking for more investment ideas beyond BP?

Once you understand BP’s story, it can be useful to widen the lens and compare it with other companies that match your risk tolerance and income goals.

This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.

Companies discussed in this article include BP.L.

Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com

Source link

Visited 3 times, 1 visit(s) today

Related Article

Markets Are Starting to Act Like They Fear a Crisis is Ahead

A broad liquidation swept stocks, commodities, and metals as the US dollar and Japanese yen surged. Unlike last week, Fed rate hike bets are fading. Is a whiff of crisis in the air? Stocks, commodities, and precious metals sold off together as correlations tightened Treasury bonds rose and Fed rate hike bets eased, pointing to

SPCX Stock Dethrones Intel As Nvidia’s Biggest Holding — Druckenmiller Buys In And Tepper Ups His Stake Over 1,600%

SpaceX overtook Intel as Nvidia’s largest disclosed holding after Nvidia added 7.71 million SpaceX shares and cut its Intel share count by 25%. Stanley Druckenmiller’s Duquesne opened a $30.5 million SpaceX position. Two of Cathie Wood’s ARK funds bought 378,515 SpaceX shares and sold 543,092 Nvidia shares on Monday. Shares of SpaceX (SPCX) overtook Intel

ASML reports transactions under its current share buyback program

ASML Netherlands BV ASML reports transactions under its current share buyback program VELDHOVEN, the Netherlands – ASML Holding N.V. (ASML) reports the following transactions, conducted under ASML’s current share buyback program. Date Total repurchased shares Weighted average price Total repurchased value 09-Nov-26 75,799 €1,324.03 €100,360,173 10-Nov-26 70,000 €1,355.01 €94,850,644 11-Nov-26 70,000 €1,394.30 €97,600,706 12-Nov-26 70,000

Nvidia Stock Is Down 32%. Is It a No-Brainer Buy at $163 or a Value Trap?

Nvidia (NASDAQ:NVDA) has gone from one of Wall Street’s hottest artificial intelligence stocks to one of its biggest sources of anxiety. Shares of the chipmaker have plunged roughly 30% from their October peak amid concerns about AI spending and the unexpected departure of longtime CEO Jensen Huang. That sell-off has pushed Nvidia’s valuation down to

Could Nvidia Be the Next Super Micro?

Nvidia (NVDA -4.12%) has suddenly become the stock no one wants to buy. Its co-founder, Jensen Huang, has resigned and is no longer the company’s president and CEO. The big concern is that Huang has been involved in an affair with a Chinese spy, which has potentially resulted in billions of dollars worth of Nvidia

Jensen Huang and Wife Transferred More Than $10.5 Billion to Family Trust in March 2026

Jensen Huang and his wife, Lori, reportedly transferred more than $10.5 billion in Nvidia stock to an irrevocable family trust in March 2026, months before the former Nvidia CEO’s alleged affairs dominated the news cycle and tanked the company’s stock. According to Barron’s, citing filings with the Securities and Exchange Commission (SEC), the couple’s transfer

Why Micron Stock Keeps Going Down

The Nvidia (NASDAQ:NVDA) fallout just keeps… falling out. And once again, it’s dragging down tech names Monday, even if they’re only tangentially related to Nvidia itself. Image source: Getty Images. Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a “Double Down” signal flashed for a little-known chipmaker called Nvidia. For the

Rolling Outages Rock U.S. Bank Stocks

Rolling Outages Rock U.S. Bank Stocks – Moby BREAKING NEWS Our analysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we’ll show you why it’s our #1 pick. Tap here. A wave of outages hit some of the biggest banks in the country Monday. Chase,

The S&P 500’s shot at 4 straight double-digit years is in Nvidia’s hands

Stocks are within reach of their fourth straight year of double-digit gains, the first since the 1990s dot-com boom. Apple (AAPL) is doing the heavy lifting, while Nvidia (NVDA) could still cost the S&P 500 (^GSPC) its four-peat. The S&P 500 closed Monday up about 8% for 2026, roughly 110 points shy of the 7,530

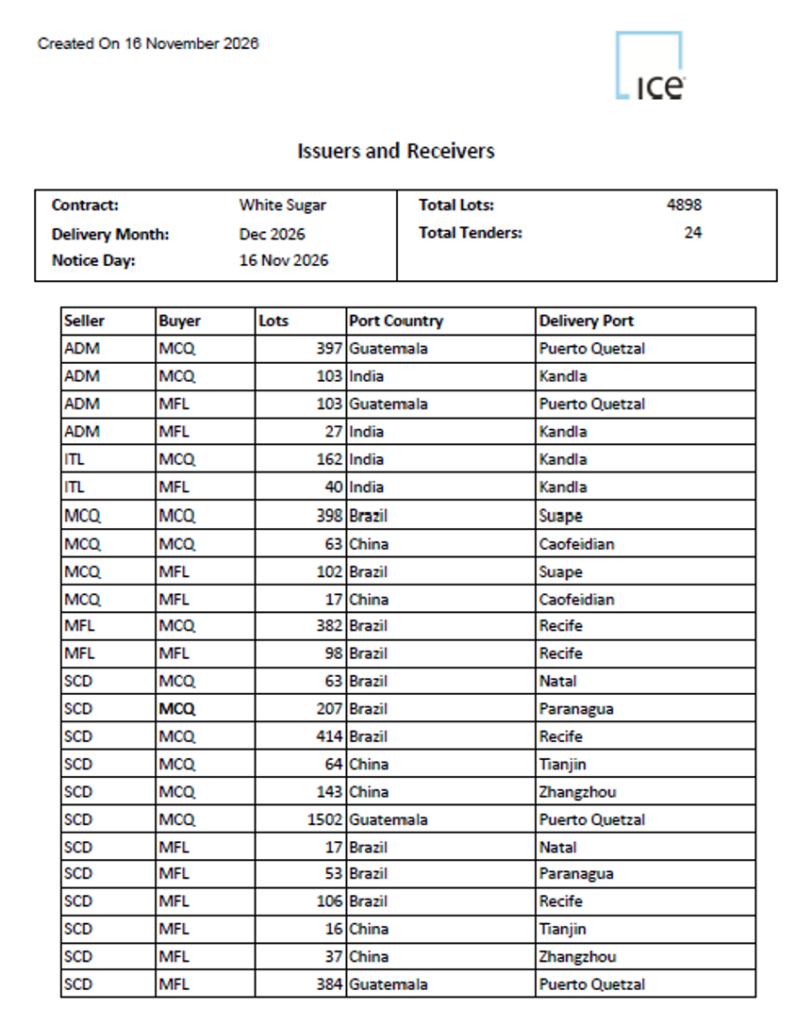
Daily Market Price Updates and Commentary 16th November 2026

  ICE Futures U.S. Sugar No.11 Contract Settlement (cUS$/lb) Open High Low Last Volume O/I Life High Life Low Mar27 18.10 -0.31 ▼ 18.41 18.43 18.07 18.10 53,922 544,768 21.29 14.42 May27 17.59 -0.32 ▼ 17.93 17.93 17.56 17.59 19,654 225,320 20.40 14.29 Jul27 17.26 -0.30 ▼ 17.56 17.56 17.23 17.24 18,502 147,699 19.81 14.27

Prediction: A Stock Market Crash Is Coming Eventually. Here’s What Investors Should Do Based on What Happened in the Last 3 Crashes.

Over the last few years, both the S&P 500 (^GSPC -1.26%) and Nasdaq Composite (^IXIC -1.94%) have benefited enormously from enthusiasm surrounding artificial intelligence (AI). History suggests a downturn is inevitable at some point, though. While this doesn’t mean a crash is coming tomorrow, one useful valuation metric suggests investors should prepare for the possibility

Ambu A/S : TRANSACTIONS UNDER AMBU’S SHARE BUYBACK PROGRAM

Real-time Estimate 08:52:36 2026-11-16 am EST 5-day change 1st Jan Change 92.10 DKK +0.49% +5.81% +4.49% Published on 11/16/2026 at 06:05 am EST Publicnow English Published: 2026-11-16 11:59:02 CET Ambu A/S – Changes in company’s own shares TRANSACTIONS UNDER AMBU’S SHARE BUYBACK PROGRAM 16.11.2026 11:59:02 CET | Ambu A/S | Changes in company’s own shares

0
Would love your thoughts, please comment.x
()
x