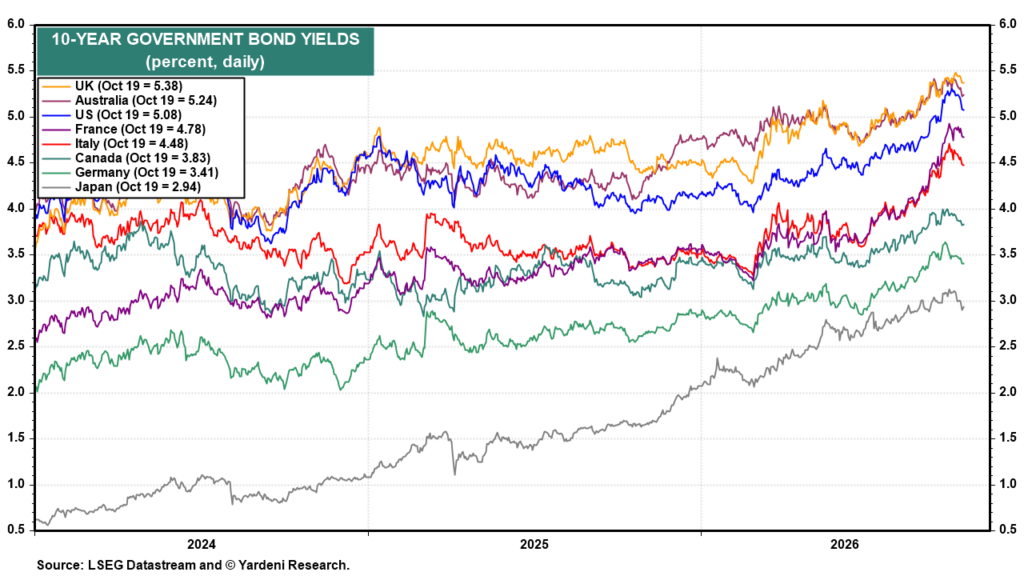
Accelerating US inflation, driven by sharp moves in energy prices, keeps pressure on interest rates and has made dependable earnings growth harder to find. That is where a group of financially solid Canadian growth stocks becomes interesting. According to analyst estimates, these companies are projected to increase profits over the next few years while maintaining balance sheet discipline. This article highlights three of the strongest candidates from that growth focused Canada list.
The three stocks highlighted here offer a compelling starting point if you want exposure to financially solid businesses with healthy high growth potential. However, if you want the absolute best, these 17 best high growth potential stocks are the cream of the crop.
Overview: Trekor Metals is a Vancouver based miner that acquires, develops and operates copper focused projects such as Gibraltar and Florence Copper.
Market Cap: CA$4.12b
Trekor Metals matters for the Healthy high growth potential theme because its copper mines are already shifting from concept to cash generating production.
“Although Florence Copper has reached its first full production quarter and is adding EBITDA for Trekor Metals, the reduction in 2026 guidance to 25 to 28 million pounds of copper from an earlier 30 to 35 million pounds target suggests ramp up risks that could leave future revenue and earnings below what higher volume assumptions would have implied.”
For investors, the key consideration is whether persistent cost pressures limit how much of that copper growth is reflected in margins.
If that margin squeeze is the question, the full narrative for Trekor Metals shows how Trekor Metals could still accelerate value if execution and copper pricing move away from current worries.

Overview: Hemlo Mining is a Toronto based gold producer built around its 100% owned Hemlo gold mine in northwestern Ontario.
Market Cap: CA$1.56b
Hemlo Mining fits the Healthy high growth potential theme because analysts expect earnings to rise about 42.92% a year as the Hemlo mine boosts gold output and ore processing efficiency. Investors get a focused producer with rising revenue forecasts and recent profitability. However, future returns depend on how a single operating hub addresses one unresolved pressure on growth sustainability.
That unresolved pressure is exactly what the 4 key rewards and 2 important warning signs (1 is major!) reveals, so you can see where Hemlo Mining’s upside could decouple from that single asset risk.