Tenaz Energy And 2 Canadian Founder Led Growth Stocks

Powered by spikes in energy prices, September inflation reached 3.7% in the latest US data and reminded investors how quickly costs can reshape returns. That kind of shock often pushes interest toward fast growing Canadian businesses where founders still own a lot of stock and have their own wealth at risk. This article highlights three such companies from our screener that blend rapid expansion with high insider commitment.

The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where owners and executives still have substantial skin in the game. However, if you want the names that matter most, these 11 high growth high conviction stocks are the strongest companies we’ve found.

Tenaz Energy is an oil and gas producer focused on offshore natural gas in the Dutch North Sea, which aligns cleanly with the fast growing, high insider commitment theme. It generates about CA$497 million from petroleum and natural gas sales and carries a market value near CA$2.34b.

On this screener, Tenaz Energy matters because its Dutch offshore gas program gives management a tangible growth engine to back their optimism, while investors get a clearer line of sight on how new wells and workovers might influence future cash generation.

“The Triton 10 barge and the pipeline of about 50 identified offshore workover opportunities provide a multi year program that is expected to add productive capacity at relatively low incremental capital, which can support net margins by spreading fixed costs over higher output.”

The real swing factor for investors is how one underlying assumption about future European gas economics ultimately flows through to those margins and growth targets.

How that gas thesis actually plays out is the spine of the full narrative for Tenaz Energy, which maps where Tenaz Energy could accelerate or stall as conditions shift.

TSX:TNZ Earnings & Revenue History as at Oct 2026

Aritzia is a womenswear retailer that designs, develops, and sells its own brands across boutiques and digital channels, with growth closely tied to its high-margin apparel business. The firm generated about CA$4.35b from apparel and has a market value near CA$16.88b.

Aritzia fits this fast-growth, high insider commitment screen because its womenswear labels are built for scale through both physical boutiques and online channels, and investor attention is now fixed on how quickly that omnichannel model can translate into sustained earnings power.

“Aritzia’s ongoing U.S. boutique rollout, with new locations reportedly paying back in under one year and management indicating room to expand from roughly 76 to 82 to at least 180 to 200 boutiques, points to a continued store-led uplift to net revenue.”
What happens if one underappreciated cost pressure quietly reshapes how much of that future growth actually turns into lasting profit?

That quiet pressure is exactly where the story gets interesting, and the full narrative for Aritzia explains how Aritzia’s rollout pace, margins, and insider alignment could be decoupling.

TSX:ATZ Revenue & Expenses Breakdown as at Oct 2026

Cascades is a packaging and tissue producer with a strong push into fiber based, recycled cardboard for e commerce and protective packaging, a key link to the fast growing, high insider ownership theme. It generated about CA$3.04b from Packaging Products and CA$1.61b from Tissue Papers, with a market value near CA$1.84b.

Cascades gives this screener a sustainability twist, because its recycled fiber packaging ties growth potential directly to e commerce shipping and low waste brands.

“Continued ramp up at the Bear Island mill toward Greenpac level efficiencies, combined with targeted reductions in chemical and material usage, should lift Packaging segment productivity and support structurally higher EBITDA margins.”

What really matters next is how one less visible cost pressure shapes whether that margin story fully reaches the bottom line.

Those quieter inputs are exactly where the Cascades story can surprise, and the full narrative for Cascades shows how efficiency gains and hidden costs could be pulling in different directions.

TSX:CAS Revenue & Expenses Breakdown as at Oct 2026

Curious About What You Might Be Missing?

Fresh ideas move first. Breakout stories, early momentum, and quality businesses get spotted before the crowd, then the best entry points start dropping away. Act now.

This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.

Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com

Source link

Visited 1 times, 1 visit(s) today

Related Article

GLOBAL MARKET CALL: Downgrading ‘Go Global’ To Market Weight

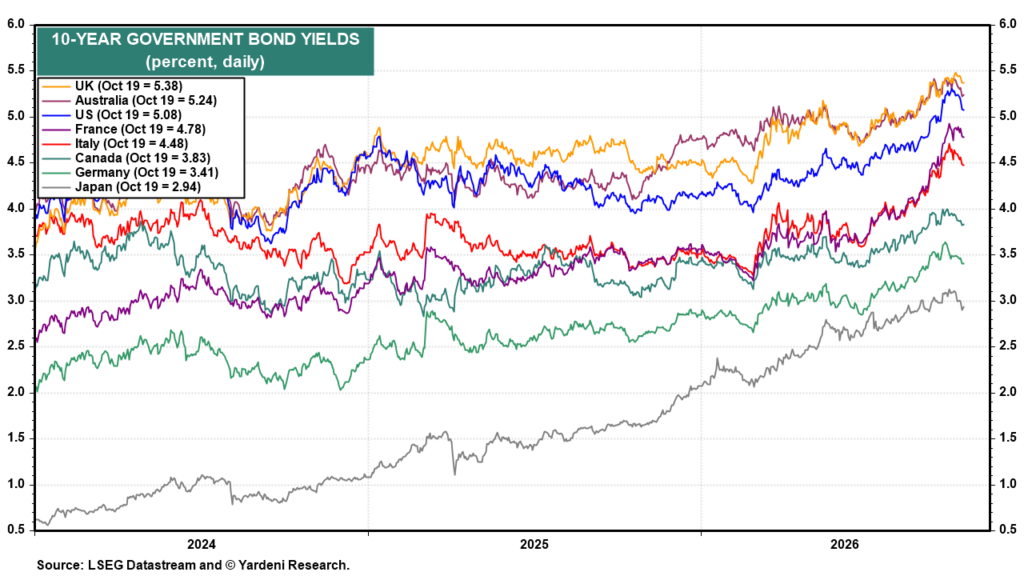
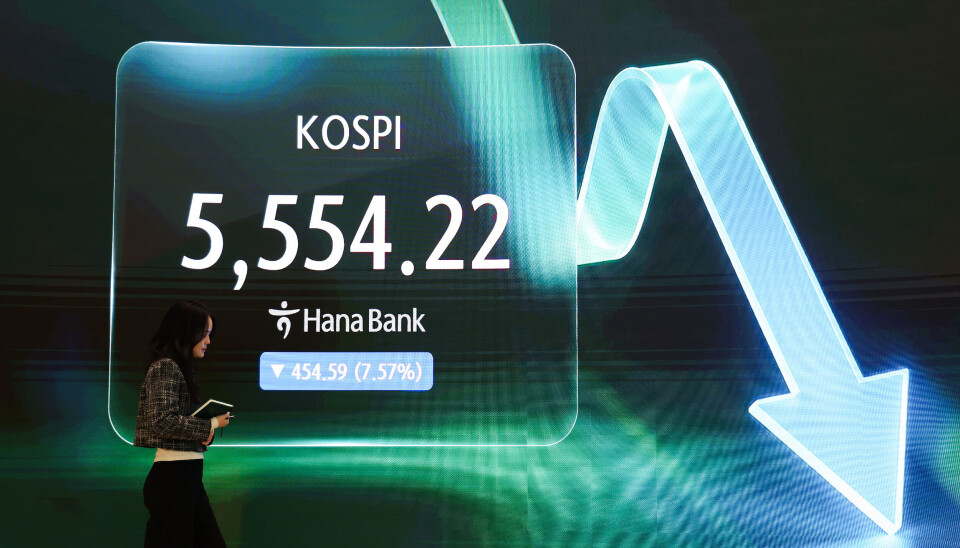
We are downgrading the “Go Global” portfolio strategy from overweight to market weight and raising “Stay Home” (in the US) from underweight to market weight. Overseas earnings remain impressive, but the rallies in emerging market economies’ stock markets have been led by just a handful of AI-related stocks. Last week’s rout in South Korea showed

Netflix Stock Has Been on a Roll. Here’s Where It Could Go Next.

Quick Read Netflix trades at $72.56 with a BUY rating and $81.87 price target, implying 13% upside despite a 23% year-to-date decline. Disney trades at 14x forward earnings with half Netflix’s revenue growth, making Netflix’s 19x multiple look reasonable by comparison. Netflix’s $4.7B record buyback quarter and $27B remaining capacity anchor the bull case alongside

SpaceX Faces Major Challenges Building Mobile Network After Spectrum Purchase

SpaceX Faces Major Challenges Building Mobile Network After Spectrum Purchase ©@Kmeel_com from pixabay via Canva, @3DSculptor from Getty Images via Canva Key Stats for SpaceX Stock Price change for SpaceX stock in last 1 month: -4% $SPCX Stock Price as of Oct. 16: $146 52-Week High: $226 $SPCX Stock Price Target: $223 What Happened? SpaceX

Netflix Stock Has Gained in the Fourth Quarter in 17 of the Last 24 Years

Netflix (NASDAQ:NFLX) has a good fourth-quarter record. Going back to 2002, the shares ended the final three months of the year up in 17 of 24 years. This count goes from the last closing price in September to the last close in December, adjusted for stock splits. And in a typical year, the rise was

Michael Burry Warns of a Stock Market ‘Supervolcano’

Photo by BeInCrypto Michael Burry, who bet against the 2008 housing bubble, says the next bear market may last a long time. The Michael Burry bear market warning rests on a century of inflation-adjusted S&P 500 data. On the surface, stocks look calm. The S&P 500 closed at a record on October 6. Yet Burry

Is AIM Award Recognition Altering The Investment Case For MP Evans Group Stock?

M.P. Evans Group recently received the Best Investor Communications award at the 2026 AIM Awards, after reporting interim revenue growth of 9%, a 25% rise in pre-tax profit and a higher dividend, supported by firm palm oil pricing. The award highlights how clear communication around commodity volatility, export regulation uncertainty and sustainability issues has become

3 Australian Growth Stocks With Earnings Growth Over 15%

Stubborn US inflation has kept interest rate risks in focus, which puts a premium on businesses that can grow through higher costs rather than just endure them. Australian fast growers where insiders own meaningful stakes offer exactly that angle, because management feels the impact of every swing alongside you. This article highlights three such stocks

Sandisk Is Dominating the S&P 500 in 2026. Can It Repeat in 2027?

Sandisk (NASDAQ: SNDK) has been the top-performing S&P 500 stock for most of 2026, until it was recently surpassed by the surging pharmaceutical company Moderna. Still, Sandisk is holding onto second place by a wide margin, and it has risen nearly 500% this year; not a bad one-year gain! However, what’s in the past is

South Korea’s NPS stock holdings lose $136 billion

The market value of the service’s holdings fell 182 trillion won ($136 billion) in three and a half months, with much of the investment concentrated in chipmakers. National Pension Service Chairman Kim Sung-joo speaks at a parliamentary audit held at the National Assembly in western Seoul on Oct. 14.YONHAP The National Pension Service’s (NPS) earlier

Super Group (SGHC) Stock Could Trade At A Discount On Its 252% Run

Super Group (SGHC) has delivered a very strong 3 year run, which puts fresh focus on whether the current share price still lines up with what its earnings can support. With the stock closing at US$11.09 most recently, the key issue is how much of the business’s profit power is already embedded in that figure.

Do Earnings Estimate Cuts Change The Bull Case For Chewy (CHWY)?

Recent reports highlight that Chewy holds an average brokerage recommendation between Strong Buy and Buy. In contrast, a lower Zacks Rank reflects more cautious earnings expectations based on negative estimate revisions. The contrast between upbeat brokerage ratings and weaker earnings estimate trends points to growing pressure on Chewy’s underlying profit outlook and business execution, rather

Kraken Robotics Stock in 3 Years: Boom, Bust, or Quietly Crushing It?

Kraken Robotics (OTC: KRKNF) is positioning itself as a leading provider of technologies supporting crewless underwater vehicles, subsea monitoring, and other maritime applications. The company is a leader in battery technologies for underwater drones and seabed mapping, and has credible offerings in other categories that could be crucial for maritime defense, offshore energy projects, and

Rusal (SEHK:486) Stock Looks Pricey As Earnings Struggle To Support It

United Company RUSAL International has seen its share price under pressure in recent years, which puts the focus squarely on whether the current Hong Kong listing price around HK$2.79 is aligned with what its earnings can support. For anyone looking at the aluminium producer today, the key issue is how that earnings profile stacks up

Is Micron’s Incredible Run About to End?

Micron (NASDAQ: MU) has been on an extraordinary run for the past year. The memory chipmaker has benefited from surging demand amid the AI revolution, combined with limited competition. Micron’s stock has skyrocketed nearly 220% in 2026, even after a recent pullback. The company, along with a handful of others, owns the vast majority of

IBM (IBM) Stock May Be 15% Undervalued As Quantum Progress Draws Focus

International Business Machines has seen its share price move around in recent months, yet the key issue for anyone looking at IBM today is whether the current US$232.14 level is supported by the cash the business can generate over time. Over the past 5 years, International Business Machines has delivered a total return of 130.1%,

Earnings Revisions Could Reshape The Plug Power Stock Story

Plug Power reaffirmed that it remains on track with its 2026 revenue guidance, supported by margin improvement efforts, reduced net cash usage, and progress on large electrolyzer agreements and hydrogen projects that underpin its role in the global hydrogen economy. Analysts have recently raised earnings estimates for Plug Power, with consensus EPS moving higher and

0
Would love your thoughts, please comment.x
()
x