2 big AI narratives wrestle with each other: What to watch this week
Even before the sell-off last week, we’ve all had the feeling of white-knuckling through the fourth quarter.
Anthropic’s (ANTH.PVT) IPO prospectus. Big Tech earnings. Bond yields through the roof. An unexpectedly tall blue wave that lifted the stock market up — and threw it back down.
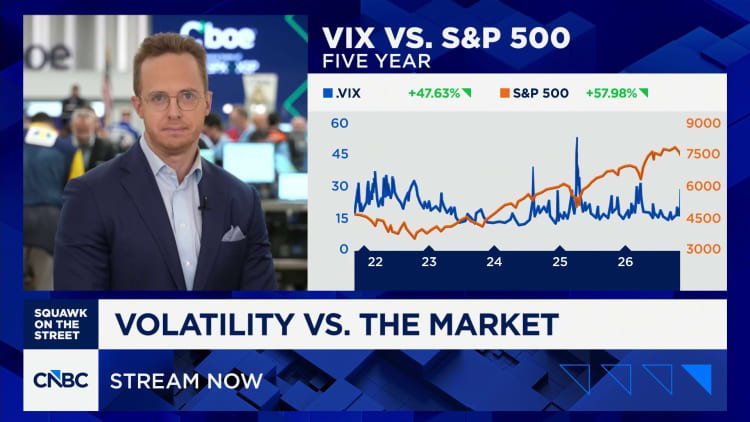
With volatility (^VIX) running hot, investors are balancing on a knife’s edge between a flywheel of angst — or a bounce.
As Goldman Sachs’ panic gauge suggested, the extremeness may signal more of Friday’s bounce to come.
It’s a new week, and we’ll have plenty of scheduled plot points to guide us.
Of particular note, we’re looking forward to CoreWeave (CRWV) quarterly results on Tuesday and Nebius Group (NBIS) and Cerebras Systems (CBRS) on Thursday, a few companies caught up in the data center destruction post-election.
What they have to say about their plans and outlook, the debt markets they’ve been tapping, and the health of their business will be at the top of mind.
Good timing to have that a mere week after midterms.
On the economic calendar, we’re in inflation mode once again, especially after that hot jobs report.
We’ll kick off the week with the New York Fed’s consumer inflation expectations before getting some actual data on Tuesday — and wholesale inflation figures on Friday to close the week.
2 big AI narratives keep wrestling with each other for control of the market
What’s more important: the chip and AI infrastructure trade or the companies that actually provide AI?
As we wrote in the Morning Brief on Friday, “A data center slowdown is bad for the stock market’s AI engine,” and “A data center slowdown is good for Big Tech’s profit machine.”
Can Google (GOOG, GOOGL), Microsoft (MSFT), and Amazon (AMZN) deliver AI at least some productivity and tools to clients with the compute they have — and make a lot of money doing so, flipping the switch from growth and scale to monetization?
Maybe! Those companies are healthily in the green since the election, doing just fine amid the broader sell-off. And while Tesla (TSLA) has sold off, SpaceX (SPCX) is mostly doing fine.
The CoreWeave AI data center is shown under construction on Oct. 21, 2026, in Kenilworth, N.J. (Stephanie Keith/Getty Images) ·Stephanie Keith via Getty Images
As DataTrek’s Nicholas Colas wrote on Thursday, you need to look at the entire week, not just the bloody Thursday, to see the bigger picture (small as that is). And it’s pretty clear that this may be reflected in the broad indexes, but it’s mostly about chips.
“As for what the market is ‘saying’ over the last 2 days, we believe the moves are AI-centric, not augurs of a looming recession,” Colas wrote, also noting that Google and Co. are doing fine.
The push-pull of the chip narrative and the hyperscaler narrative is the pulse our fingers are on right now.
A big inflation check after a booming jobs report
Friday’s blowout jobs report of 165,000 jobs delivered an unexpected verdict about the current state of the labor market: It’s better than fine.
Even September’s underwhelming 29,000 jobs were adjusted upward to 60,000.
Good for breaking the “low-fire, low-hire” ice, if this represents the beginning of a trend. As every Fed chair likes to remind us, one month doesn’t mean anything by itself.
Customers check fruit at a grocery store in New York on Oct. 14, 2026. (Zhang Fengguo/Xinhua via Getty Images) ·Xinhua News Agency via Getty Images
But with Tuesday and Friday’s big inflation reports for October, we’ll have more than just one data point to work with, and two (or more) hot pieces of economic data could start to make some people sweat.
We are keeping one research note from Apollo’s Torsten Sløk that caught our attention last week at the top of our mind: that the Fed’s rates needed to bring inflation down its 2% target could be as high as 6.75%. (Disclosure: Yahoo is a portfolio company of funds managed by affiliates of Apollo Global Management.)
While the data center sell-off is obviously important, inflation still matters as much as anything.
Bloomberg’s average analyst estimate has core inflation rising 0.2%, slowing down from 0.3% last month.
A ton of post-election Fed speak is coming
Amid all the data will be a lot of commentary from the people who read the data — and decide what to do with it.
The Fed’s Goolsbee and Bowman speak on Monday; Waller and Bowman (again) on Tuesday; Barr, Barkin, and Logan on Thursday; and Williams, Jefferson, and Bowman (again) on Friday.
We love seeing our public officials putting in the work. But the market loves guidance and FedSpeak even more and is hoping to be given more of a lens through which to read all of this data and get a better picture of how the Fed sees the economy — and perhaps even the sell-off, depending on what topics come up and how forthcoming they feel like being.
With Fed Chair Warsh settling into a cryptic, taciturn no-forward-guidance rhythm, it’s up to these guys — who may also feel more emboldened post-midterms.
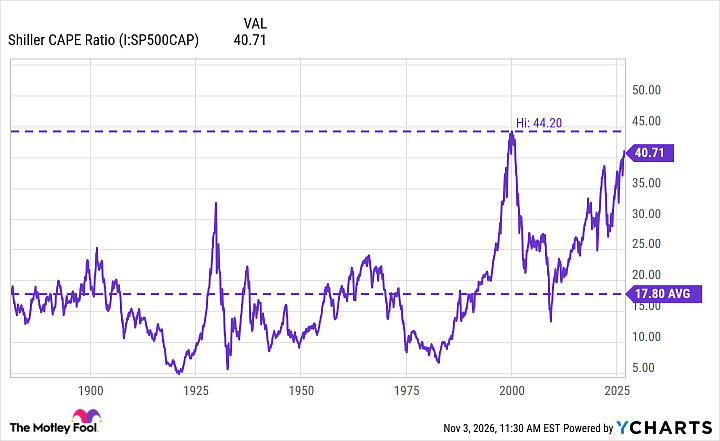
Is a market crash coming? That’s the question on many investors’ minds today as the strong bull market continues. The S&P 500 (SNPINDEX: ^GSPC) has more than doubled over the past four years, and it’s up 12% year to date. Artificial intelligence (AI) euphoria is still driving the market, but there are signs that suggest
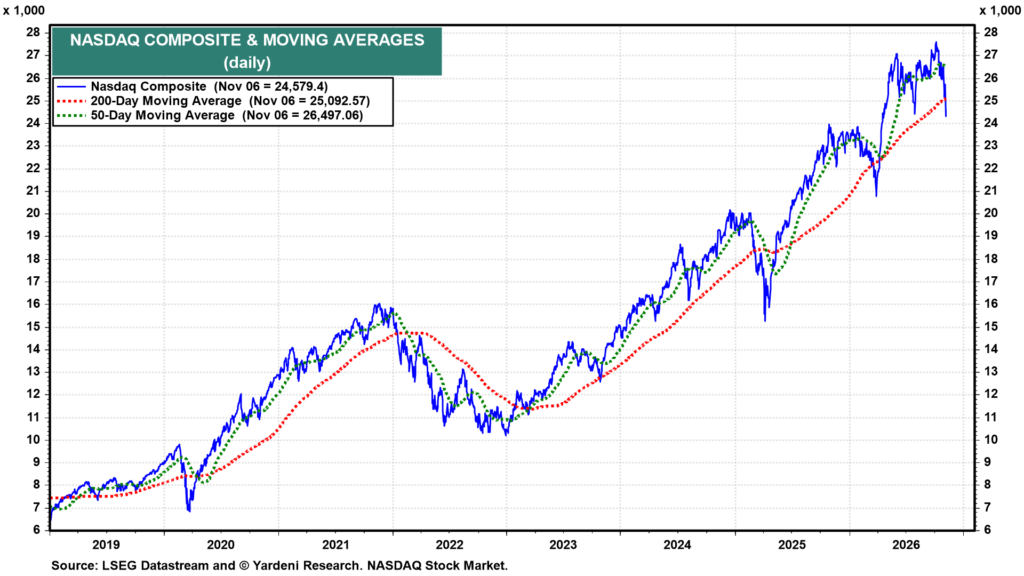
The S&P 500 (^GSPC +0.31%) fell 4.4% on Thursday, its worst day since April 2025, while the Nasdaq slumped 5.5%. That deep sell-off pushed the Nasdaq into correction territory, with it tumbling more than 10% below its recent record. Nobody knows whether that’s the start of something bigger. But it landed in a market already
Quick Read Berkshire Hathaway (BRK-B) sits on $377 billion in cash and ramped up Q3 buybacks to $10 billion, signaling management sees value in the stock. Berkshire has gained 14% this year while the S&P 500 rose 8%, as its railroad, insurance and energy mix sidestepped the AI rally. Markel, often called a mini-Berkshire, runs
Last month, Wall Street and investors celebrated the fourth anniversary of the current bull market. Both the benchmark S&P 500 (^GSPC +0.31%) and growth-fueled Nasdaq Composite (^IXIC +1.09%) have more than doubled from their 2022 bear market lows, while the iconic Dow Jones Industrial Average (^DJI -0.46%) has rallied as much as 90%. A confluence
Seoul Mayor Oh Se-hoon. News1 “Focus on pumping up prices before the election… nine circuit breakers in five months” On Saturday, Oh criticized the government’s stock market policy through his social media accounts. “Last Friday the Kospi broke below the 5,000 line and a circuit breaker was triggered,” he wrote. “Of the 11 circuit breakers
Fundamental Backdrop and Market Sentiment I wrote on 1st November that the best trades for the week would be: Short of the EUR/USD currency pair below $1.1300. This pair fell over the week by 0.17%. A summary of last week’s most important data in the market: US Average Hourly Earnings – increased at a slightly
An agreement to acquire optical components provider Lumentum Holdings (LITE +5.67%) in an all-stock transaction valued at $115 billion sent Marvell Technology down 28.1% this week. Marvell Technology stock changed hands at $141.20 as of the close on Friday, Nov. 6, having dropped 32% from Friday, Oct. 30’s close, according to data provided by S&P
Companies that generate positive operating cash flow can allocate their capital in various ways. Of course, reinvesting in the business is what many long-term investors appreciate, as it can boost intrinsic value over time. There are also mergers and acquisitions, as well as paying down debt. When it comes to returning capital to investors, companies
Wall Street’s tumultuous midterm election week kicked off with a celebration among investors. On Wednesday, stocks soared after Democrats swept both chambers of Congress. The Dow (^DJI) surged more than 1,500 points. The S&P 500 (^GSPC) rallied nearly 2%. And in less than 24 hours, stocks reversed course, plunging Thursday as Wall Street and Main
Shares of Micron Technology and Sandisk have soared 280% and 457%, respectively, over the past year as demand for memory processors in data centers jumped. Spending for artificial intelligence (AI) infrastructure isn’t slowing down right now — as Alphabet‘s (GOOGL +0.78%) (GOOG +0.78%) recent quarterly results show — and that’s great news for Micron and Sandisk
At age 7, when most children are collecting Pokémon cards and asking for Messi soccer cleats for their birthdays, Yotam Raz of Moshav Beit Yitzhak, a village in central Israel, wanted to learn how to make money. It was during the COVID-19 pandemic, and he used the lockdowns to make natural soaps, which he later
The stock market dived last week. Investors priced in political backlash against data centers after Democrats swept Congress. We anticipated buying opportunities after the midterm elections, and Thursday’s selloff delivered some. This remains an earnings-led bull market. Valuations are falling while earnings are soaring. We still view the AI backlash as another speed bump, not
It’s a rally. It’s a sell-off. At the end of the week, the only thing that was clear was confusion. Investors were hoping to get clarity with the U.S. midterm elections behind them. Instead, they got more volatility. The reason is uncertainty about future regulation surrounding data centers. The conventional wisdom suggests it may not
Political gridlock, strong earnings, and a historical pattern that hasn’t failed in 21 midterm election cycles Listen to the audio version of this article (generated by AI). Editor’s Note: The midterm elections are behind us, and Washington is gearing up for another round of political battles. But I still feel optimistic – and so does
Rolls-Royce’s (BMW.DE) well-heeled clients aren’t pumping the brakes on new commissions, despite a choppy stock market and lingering economic worries, according to the automaker’s top executive in North America. “Honestly, no,” Nick Keen, president of Rolls-Royce Motor Cars North America, told Yahoo Finance at the Wynn Concours in Las Vegas when asked if clients are
It’s been said that bull markets end when good news fails to boost prices, and that bear markets end when bad news fails to send prices lower. On that note, Bitcoin (BTC +0.28%) is 33.7% above its bear market lows in late June. Most of the high-flying artificial intelligence (AI) value-chain stocks, on the other
The S&P 500 (^GSPC +0.31%) is up 10.8% this year, but it’s been falling over the past few weeks. If it falls any lower, it will break its streak of double-digit annual gains over the past four years. Between soaring artificial intelligence (AI) spend, high inflation, steady interest rates, and the results of Tuesday’s U.S.
Wall Street partied the day after the midterms and woke up Thursday to tech’s worst day since the 2020 COVID crash. Strip out the AI trade, though, and most stocks barely noticed. The equal-weight S&P 500 (RSP), a stand-in for the typical stock, closed at a record Wednesday and ended the week within about 1%
There’s nothing like a good selloff to turn a trader into an investor – so the saying goes. It’s an adage that echoes the sentiment of an even older one: buy when there’s blood in the streets. The maxims ring true after Thursday’s selloff in stocks that sent the Cboe Volatility Index (VIX) to its
Many investors don’t believe the terms “Magnificent Seven” and “bargain stocks” usually belong in the same sentence. And it’s easy to see why. Over the past five years, the Magnificent Seven has gained more than 180% as a group, more than double the S&P 500’s total return over the same period. But I wouldn’t be