Inflation in the US hit 3.7% in September, driven by sharp jumps in energy costs, which puts profitable, financially sound growth stories in sharper focus for many investors. Companies that analysts expect to grow earnings quickly while still keeping their balance sheets in decent shape can look attractive when everyday costs feel higher. This article highlights three such high potential stocks from our screener and explains what sets each apart.
The three stocks highlighted here offer a compelling starting point if you want exposure to financially healthy businesses with high earnings growth potential. However, if you want the names that matter most, these 487 best high growth potential stocks are the strongest companies we’ve found.
NVIDIA is best known for chips that power gaming and graphics. Yet the real “Healthy high growth potential” angle comes from its Compute & Networking unit supplying GPUs, networking, and AI software that run large language models for cloud and enterprise customers worldwide.
NVIDIA generates about US$275.4b from Compute & Networking and US$27.6b from Graphics, making data center AI infrastructure the dominant revenue stream, and the business carries a market value of roughly US$5,170.6b.
That AI infrastructure focus is what links NVIDIA so strongly to this screener. It sets up a clear earnings growth narrative that hinges on whether its technology stack can keep attracting the biggest cloud and enterprise workloads.
“Uptake of an open-source/cheaper/better platform than Nvidia’s CUDA would heavily undermine Nvidia’s moat and enable any sizeable firm to directly engage semiconductor manufacturers, such as TSMC, to produce their own chips, stealing away Nvidia’s high margin products.”
Everything depends on how one unresolved competitive pressure shapes future pricing power and keeps those high margins intact.
To see how that competitive risk could reshape pricing power, read the full narrative for NVIDIA and see how NVIDIA’s AI story could keep accelerating beyond CUDA.
NasdaqGS:NVDA Earnings & Revenue Growth as at Oct 2026
Advanced Micro Devices leans into the Healthy high growth potential theme through its Data Center business, where EPYC server processors and Instinct AI accelerators serve hyperscale clouds, while Client, Gaming and Embedded lines still add meaningful sales, and the overall company carries a market value near US$863.2b.
Advanced Micro Devices builds the chips and full AI infrastructure that power everything from cloud data centers to gaming rigs and adaptive computing. That breadth matters for this screener, because the earnings story increasingly turns on how effectively AMD converts its AI push into sustained profit growth.
“Multi gigawatt, multi generation Helios rack scale AI system commitments from large customers such as OpenAI, Meta and Anthropic, combined with staged production ramps from late Q3 2026 through 2027, give AMD a path to secure data center AI revenue streams. These could scale absolute gross profit even if MI450 margins stay slightly below the corporate average.”
What happens to that profit path depends on how a single pressure around future pricing and mix between accelerators and higher margin products eventually resolves.
That pressure point is exactly what the full narrative for Advanced Micro Devices unpacks, showing how Advanced Micro Devices could turn Helios demand into accelerating earnings power beyond the headline AI story.
NasdaqGS:AMD Earnings & Revenue Growth as at Oct 2026
USA Rare Earth focuses on mining and processing critical rare earth minerals that feed electric mobility and clean energy technologies, with investors watching how this early stage producer moves toward commercial scale. The business is valued at about US$4b by the market.
USA Rare Earth gives this screener exposure to the building blocks of the green economy, since its rare earth projects are tied directly to electric vehicles and clean energy hardware rather than more traditional metals.
“The award comes through the DOE’s Critical Materials Innovation, Efficiency and Alternatives program and is aimed at advancing a pilot‑scale rare earth element (REE) separations project within the United States.”
What really matters now is how one hard to price shift in future project economics affects the path from forecast growth to actual cash generation.
That turning point starts with the project economics the full narrative for USA Rare Earth lays out, highlighting where USA Rare Earth could accelerate from funded pilot work to scaled cash generation.
NasdaqGM:USAR Earnings & Revenue Growth as at Oct 2026
Seeking Fresh Alternatives Before They Fly
Market movers can shift quickly, and some investors look for potential breakout candidates before momentum is widely recognized. Explore curated ideas that may still be under the radar and consider them early.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
BP updated its third quarter 2026 production guidance, now expecting reported upstream output of 2,190 mboe/d to 2,240 mboe/d, split between Oil production & operations of 1,415 mboe/d to 1,445 mboe/d and Gas & low carbon energy of 775 mboe/d to 795 mboe/d. The more granular breakdown between oil operations and gas and low carbon
Quick Read Nine companies, including Broadcom and Verizon, formally objected to OKX-ICE’s plan to list 63 tokenized versions of their shares on a blockchain. An SEC rule established September 17 grants companies 30 days to block tokenized listings after receiving written notice from an exchange. Synthetic products offering only price exposure can still trade without
indie Semiconductor has been busy, from reporting Q1 2026 revenue of US$55.5 million and a new US$25 million radar order to agreeing a €40 million CMOS sensor deal with ams OSRAM and launching the iND881 edge AI chip. For indie Semiconductor shareholders, the loss over the past year was 65.8%, including dividends. If you had
Accelerating US inflation, driven by sharp moves in energy prices, keeps pressure on interest rates and has made dependable earnings growth harder to find. That is where a group of financially solid Canadian growth stocks becomes interesting. According to analyst estimates, these companies are projected to increase profits over the next few years while maintaining
Last December, President Donald Trump issued Executive Order 14370, intended to fast-track the rescheduling of marijuana to Schedule III, in turn paving the way for federal regulatory clarity. At the time, marijuana stocks, including Canopy Growth (NASDAQ: CGC), surged sharply on the news, with Canopy itself surging from $1.15 to nearly $2 per share. Shares
Mike McGlone said Bitcoin was “rolling over from an extended plateau akin to 2018 and 2022.” He said that “dominoes could tumble” if it failed to prove strength. Fidelity’s Jurrien Timmer said “a new 4-year cycle bull market could be underway” for Bitcoin, adding that “bull markets rarely start with” a narrative. Mike McGlone, a
Powered by spikes in energy prices, September inflation reached 3.7% in the latest US data and reminded investors how quickly costs can reshape returns. That kind of shock often pushes interest toward fast growing Canadian businesses where founders still own a lot of stock and have their own wealth at risk. This article highlights three
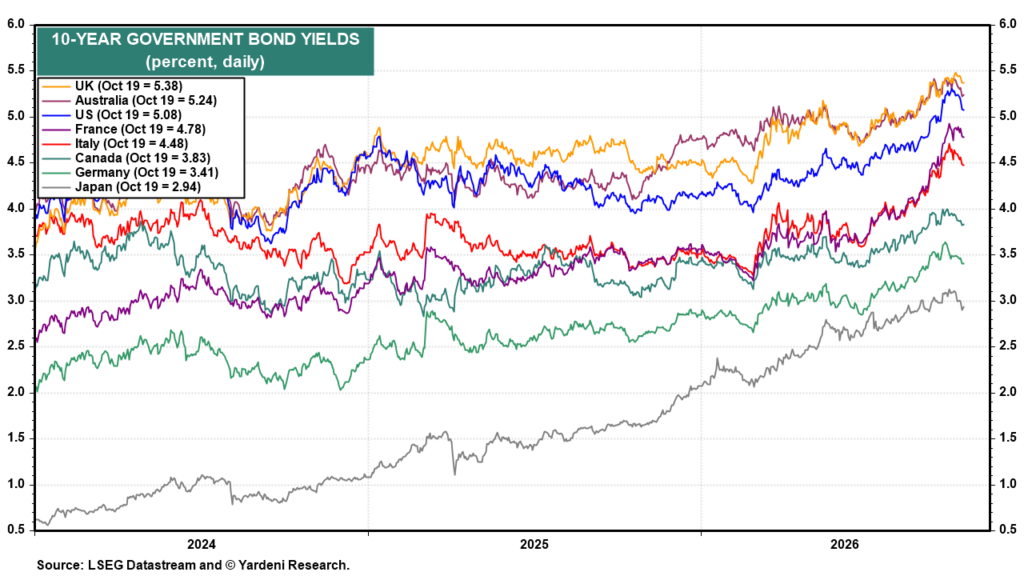
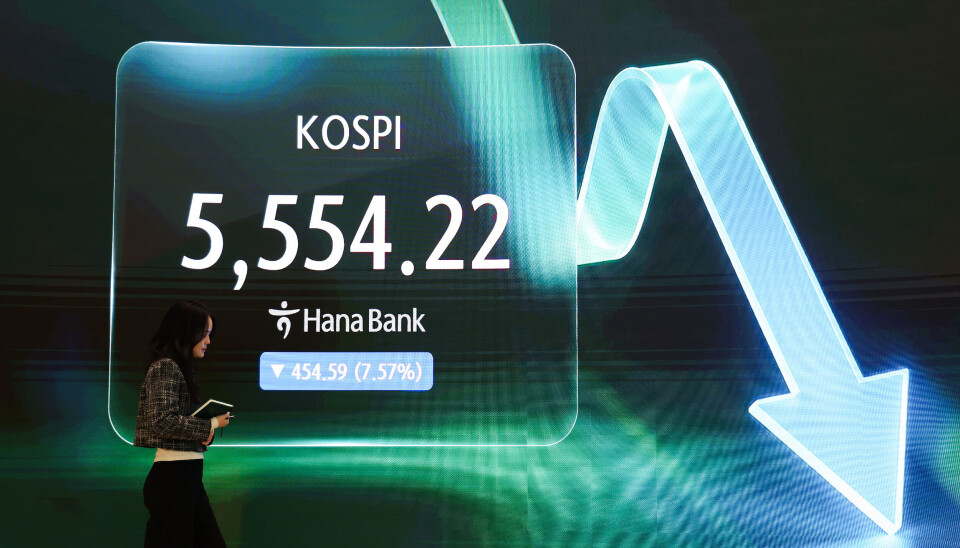
We are downgrading the “Go Global” portfolio strategy from overweight to market weight and raising “Stay Home” (in the US) from underweight to market weight. Overseas earnings remain impressive, but the rallies in emerging market economies’ stock markets have been led by just a handful of AI-related stocks. Last week’s rout in South Korea showed
Quick Read Netflix trades at $72.56 with a BUY rating and $81.87 price target, implying 13% upside despite a 23% year-to-date decline. Disney trades at 14x forward earnings with half Netflix’s revenue growth, making Netflix’s 19x multiple look reasonable by comparison. Netflix’s $4.7B record buyback quarter and $27B remaining capacity anchor the bull case alongside
Netflix (NASDAQ:NFLX) has a good fourth-quarter record. Going back to 2002, the shares ended the final three months of the year up in 17 of 24 years. This count goes from the last closing price in September to the last close in December, adjusted for stock splits. And in a typical year, the rise was
Memory chip specialist Micron Technology (NASDAQ: MU) has seen its shares drop about 24% from their all-time high of 1,255. That might seem like a lot, and you might find yourself feeling sorry for its shareholders, but don’t — because Micron’s shares are actually up 445% over the past year — more than quintupling their
Two hundred dollars a month doesn’t sound like much when your goal is to build a $1 million net worth. But that’s why long-term investing in stocks is so exciting. It’s a very achievable goal if you understand the math behind it. The Vanguard S&P 500 ETF (NYSEMKT: VOO) is a great tool to use
Photo by BeInCrypto Michael Burry, who bet against the 2008 housing bubble, says the next bear market may last a long time. The Michael Burry bear market warning rests on a century of inflation-adjusted S&P 500 data. On the surface, stocks look calm. The S&P 500 closed at a record on October 6. Yet Burry
M.P. Evans Group recently received the Best Investor Communications award at the 2026 AIM Awards, after reporting interim revenue growth of 9%, a 25% rise in pre-tax profit and a higher dividend, supported by firm palm oil pricing. The award highlights how clear communication around commodity volatility, export regulation uncertainty and sustainability issues has become
Stubborn US inflation has kept interest rate risks in focus, which puts a premium on businesses that can grow through higher costs rather than just endure them. Australian fast growers where insiders own meaningful stakes offer exactly that angle, because management feels the impact of every swing alongside you. This article highlights three such stocks
Sandisk (NASDAQ: SNDK) has been the top-performing S&P 500 stock for most of 2026, until it was recently surpassed by the surging pharmaceutical company Moderna. Still, Sandisk is holding onto second place by a wide margin, and it has risen nearly 500% this year; not a bad one-year gain! However, what’s in the past is
The market value of the service’s holdings fell 182 trillion won ($136 billion) in three and a half months, with much of the investment concentrated in chipmakers. National Pension Service Chairman Kim Sung-joo speaks at a parliamentary audit held at the National Assembly in western Seoul on Oct. 14.YONHAP The National Pension Service’s (NPS) earlier
Super Group (SGHC) has delivered a very strong 3 year run, which puts fresh focus on whether the current share price still lines up with what its earnings can support. With the stock closing at US$11.09 most recently, the key issue is how much of the business’s profit power is already embedded in that figure.
Recent reports highlight that Chewy holds an average brokerage recommendation between Strong Buy and Buy. In contrast, a lower Zacks Rank reflects more cautious earnings expectations based on negative estimate revisions. The contrast between upbeat brokerage ratings and weaker earnings estimate trends points to growing pressure on Chewy’s underlying profit outlook and business execution, rather