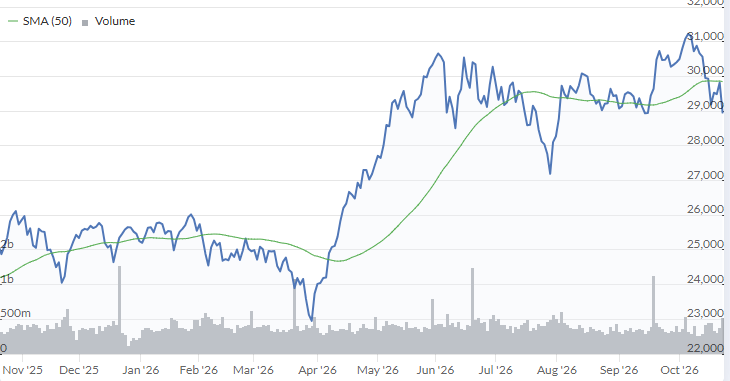
Bloom Energy (NYSE:BE) delivered another blowout quarter, smashing estimates and growing profits faster than sales. Yet, its stock plunged after earnings and was down more than 12% as of Friday noon.
The company sells solid-oxide fuel cell servers that turn natural gas into electricity right at a customer’s site. Artificial intelligence (AI) data centers desperately need that because the existing grid needs years to build additional capacity.
Missed AI’s “Act 1”? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »
Bloom Energy can bypass the grid and swiftly deliver clean, reliable, 24/7 power to hyperscalers and data center operators. It delivered a complete fuel-cell system to Oracle (NYSE:ORCL) in 55 days last year. The tech giant was so impressed that it expanded its partnership for up to 2.8 gigawatts (GW) earlier this year.
So, what is happening with Bloom Energy stock? Why is it dropping like a rock – down 30% in one month, as of this writing?

Image source: Getty Images.
A bumper quarter and 2027 outlook
Revenue soared 138% year over year to a record $1.2 billion in the third quarter. Product sales, the fuel cell systems Bloom Energy ships to customers, topped $1 billion in sales in a single quarter for the first time.
Profit grew even faster. Adjusted operating margin jumped to 23.1% from 8.9% as revenue more than doubled while operating expenses rose only 26%. CFO Simon Edwards added that operating income in this single quarter surpassed what Bloom earned in all of 2025.
Then management raised its full-year revenue outlook for the third time this year. It now expects 2026 revenue of $4.5 billion, or about 122% growth.
Here’s the kicker: Earlier in the year, Bloom Energy was guiding for a “humble” 60% revenue growth for the year. It has more than doubled its trajectory in just a couple of quarters.
So what’s hurting the stock? The only metric I could find that may have miffed investors is cash burn. Bloom Energy posted negative free cash flow of $181 million in Q3.
Should investors worry? Hardly, because context is everything.
Is Bloom Energy stock a buy?
Demand is exploding, so Bloom Energy spent $153 million last quarter to scale up capacity as fast as possible. Data centers are built in phases, and Bloom is ready with its servers at each phase so operators don’t have to wait.
That speed is everything for data centers.