A Once-in-a-Decade Investment Opportunity: The Best Artificial Intelligence (AI) Stock to Buy in 2026

Nvidia has been the star of the artificial intelligence show for three years, and its stellar performance doesn’t appear to be coming to an end.

For the last three years, the stock market’s biggest tailwinds have stemmed from virtually anything that touches artificial intelligence (AI). Within the AI landscape, semiconductor giant Nvidia (NVDA +0.02%) has emerged as the most influential business.

While Nvidia’s nearly 1,000% stock gains throughout the AI revolution might suggest you’ve missed the boat, smart investors understand that the chip behemoth’s story is really just getting started.

Let’s break down what makes Nvidia such a unique opportunity and assess why now is as good a time as ever to scoop up some shares.

Image source: Nvidia.

AI infrastructure isn’t going anywhere

The chart below illustrates quarterly trends in capital expenditures (capex) among AI hyperscalers.

AMZN Capital Expenditures (Quarterly) Chart

AMZN Capital Expenditures (Quarterly) data by YCharts.

Indeed, big tech has spent the last three years procuring as many graphics processing units (GPUs) as possible to outfit next-generation data centers. But the subtle theme from the financial profile above is that this spending activity isn’t slowing. In fact, it’s accelerating among the major players.

While Amazon Web Services (AWS), Google Cloud Platform (GCP), and Microsoft Azure are designing their own custom hardware, these cloud infrastructure giants still partner heavily with Nvidia.

For example, OpenAI recently signed a $38 billion contract with AWS to rent clusters of Nvidia’s GB200 and GB300 GPUs. Per the agreement, OpenAI is targeting all capacity to be deployed “before the end of 2026” with the potential to ramp further.

In a similar fashion, Anthropic agreed to buy $30 billion of compute capacity from Azure in a deal featuring Nvidia’s Grace Blackwell and upcoming Vera Rubin chip architecture.

Here’s the big picture: Nvidia is becoming a key layer of the overall AI infrastructure foundation. While AWS and Azure may fetch more attention from their respective agreements with OpenAI and Anthropic, Nvidia is really the hidden winner here.

As these build-outs come online throughout 2026 and beyond, Nvidia is well positioned to experience continued, robust revenue and profit acceleration this year and throughout the rest of the decade.

Watch out for new revenue streams

I expect Nvidia’s data center segment to continue to be the most meaningful driver of growth this year.

However, smart investors will be listening closely to what CEO Jensen Huang has to say about new revenue streams in 2026 and how these businesses could reshape Nvidia’s future roadmap.

Nvidia recently invested $5 billion into Intel as the two semiconductor leaders join forces to design custom central processing units (CPUs) and PC systems. While these new architectures will take time to design and then fully deploy, I expect that 2026 could feature some announcements with original equipment manufacturers (OEM) that plan to integrate Nvidia’s new hardware outside of its current AI accelerator lineup.

In addition, Nvidia made a $1 billion strategic investment in telecommunications specialist Nokia in late 2025. Per the press release, AI radio access networks (RAN) is a $200 billion market. Not only does Nvidia have a first-mover advantage in this emerging market, but “trials are expected to begin in 2026” — signaling Nvidia is diversifying outside of its core competencies and investors could see some nominal revenue mix shift beginning this year.

Lastly, I think a hidden catalyst for this year could be Nvidia’s $20 billion licensing deal with Groq. While it’s difficult to forecast how much this relationship could move the needle for Nvidia, I think 2026 could be the beginning of a pivotal shift in how Nvidia plans to complement its AI training expertise with deeper inference integrations through some help from Groq.

Nvidia Stock Quote

Today’s Change

(0.02%) $0.04

Current Price

$184.90

Nvidia’s valuation is too good to ignore

As of this Jan. 8, Nvidia traded at a forward price-to-earnings (P/E) multiple of 24.7. On the surface, this may look expensive. However, a more thorough look under the hood suggests that Nvidia stock may be dirt cheap.
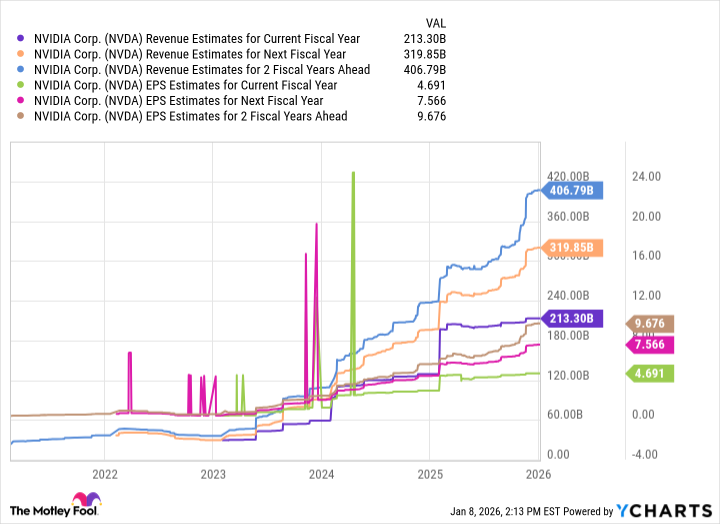
NVDA Revenue Estimates for Current Fiscal Year Chart

NVDA Revenue Estimates for Current Fiscal Year data by YCharts.

According to Wall Street’s consensus estimates, Nvidia’s revenue and earnings per share (EPS) are expected to double over the next two years. While this is impressive, I think these figures could be understated.

As outlined above, Nvidia has a number of multiyear commitments from the hyperscalers as well as the potential to disrupt several new verticals. The impact of these developments are virtually impossible for sell-side analysts to model in their projections given the uncertainty around timelines and the magnitude of how these applications scale.

Perhaps a more revealing valuation metric for a hypergrowth business like Nvidia is to look at the price/earnings-to-growth ratio (PEG ratio). This ratio is useful because it is forward-looking and accounts for long-term earnings growth potential. In general, a PEG below 1 suggests a company is undervalued. Right now, Nvidia’s PEG ratio is a modest 0.72 — its lowest level in a year.

At the end of the day, Nvidia remains a category-defining company with immense pricing power benefiting from a multiyear structural AI capex cycle that’s helping it evolve into more of a diversified platform business.

All told, I think Nvidia is on a path to continue growing throughout the rest of the decade with 2026 being an important time for the company’s evolution from chip designer to multifaceted ecosystem scaling from increased investment across both hardware and software.

For these reasons, I see Nvidia as the most compelling buy-and-hold AI stock of the decade and think now is a great opportunity to pounce on its reasonable price point.
Source link

Visited 1 times, 1 visit(s) today

Related Article

US stock futures fall amid key Democratic midterm election wins

Robert Wolf, a former economic advisor to Obama, and Steve Cortes, a former Trump campaign advisor, discuss the midterm election’s impact on Wall Street. U.S. stock futures fell sharply as Democrats scored key victories in the midterm elections and the Fox News Decision Desk projected the party will take control of both chambers of Congress.

Why Capri Holdings Stock Popped 32% in October

Shares of Capri Holdings (NYSE:CPRI) were on the move last month, jumping at the end of the month on a strong earnings report after earlier gains on speculation of a buyout. Capri also seemed to benefit from a rotation in consumer discretionary stocks as investors sold AI stocks last month. Missed Nvidia in 2009? This

Indonesia regulator announces sanctions for alleged stock market violations

End-of-day quote 2026-11-03 5-day change 1st Jan Change 324.00 IDR -2.41% -3.57% -51.28% Published on 11/03/2026 at 11:16 pm EST Reuters This article is reserved for our members. Log in to continue Log inCreate an account 11:16pm Indonesia regulator announces sanctions for alleged stock market violations RE Oct. 29 PT Panorama Sentrawisata Tbk Reports Earnings

Why Shake Shack Stock Jumped 20% in October

Shake Shack (NYSE:SHAK) stock was moving higher last month in a broader rotation into restaurant stocks as investors sold AI stocks and rotated into undervalued sectors like restaurants. There was no major news item that drove the stock up last month, but Shake Shack did benefit from its announcement that it would expand into Brazil,

Jim Cramer sees signs of life in tech stocks — but not from the usual winners

CNBC’s Jim Cramer said Tuesday that a new group of technology stocks may be emerging as market leaders. While heavyweights such as Nvidia, Microsoft, Alphabet and Meta have struggled to sustain rallies in recent weeks, other companies are showing signs of strength. That was evident during Tuesday’s session as gains from Broadcom and Micron supported

Syndax Pharmaceuticals Stock Gains Focus After Revenue Growth And Pipeline Progress

Syndax Pharmaceuticals reported Q3 2026 revenue of US$83.3 million versus US$45.87 million a year earlier, with the quarterly net loss at US$49.43 million and basic loss per share at US$0.55. The company also announced a CFO transition effective November 9, 2026. Growing contributions from Revuforj and Niktimvo, alongside pipeline spending that kept the business in

Ball (BALL) Stock Looks Reasonable On Its Earnings Support

Ball has logged a strong share price run in the past year, which puts a sharper spotlight on whether the current tag is justified by what the business actually earns. With that kind of move already on the board, the question now is how comfortably Ball’s earnings can carry the valuation. The stock is up

Should You Buy Qualcomm Stock Before Its Nov. 4 Report?

Qualcomm (NASDAQ:QCOM) shares slid 11% on Oct. 30 to close at $164.79. The company didn’t release any news of its own that day. Instead, it was caught in a broad chip sell-off after Intel forecast less revenue in the fourth quarter than in the third and warned the PC slowdown might last until at least

Pinnacle West Capital Corporation Q3 2026 Earnings Call Summary

Pinnacle West Capital Corporation Q3 2026 Earnings Call Summary – Moby Strategic Drivers of Record Growth and Operational Performance Our analysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we’ll show you why it’s our #1 pick. Tap here. Record-breaking summer demand was met through

3 Stocks That Did Well the Last Time the Fed Raised Rates Aggressively

The Federal Reserve recently raised interest rates for the first time in years, and more rate hikes are expected. Another hike may even happen before the end of the year. How much higher rates end up going is anyone’s guess at this point, as inflation remains elevated and the war in Iran doesn’t appear to

November Stock Market Outlook: How to Position Your Portfolio for the Remainder of 2026

Stock Market Outlook Key Takeaways The US stock market is trading at a 10% discount to a composite of our valuations AI enthusiasm is evolving into AI accountability Maintain a barbell-shaped portfolio: Overweight value and growth, underweight core Based on a composite of our intrinsic valuations of the stocks we cover included in the Morningstar

Is Brighthouse Financial, Inc. (BHF) Stock Facing a Major Regulatory Hurdle?

Greenlight Capital, an investment management firm, recently released its Q3 2026 investor letter. A copy of the letter can be downloaded here. The funds returned -3.3% in the third quarter of 2026, compared with a 2.3% gain for the S&P 500, bringing their year-to-date return to -1.5% against the index’s 12.7% advance. The disappointing performance

Why Sandisk Stock Dropped 24% in October

Sandisk (NASDAQ: SNDK) stock lost 24% in October, according to data provided by S&P Global Market Intelligence. Although it reported another quarter of fantastic growth, the market is worried about a slowdown in the memory cycle. Memory is dominating right now Sandisk makes many of the products important for all kinds of technology, and it’s

Bill Ackman warns of ‘casino’ stock market trading

Pershing Square CEO Bill Ackman speaks on CNBC’s “Squawk Box,” Nov. 3, 2026. CNBC Bill Ackman worries that the stock market is broken, saying the rise of speculative trading is leading to wild price swings thanks to the amount of leverage in the system. “Every number of days, I feel like markets are broken,” Ackman

Here’s My Top Stock to Buy for November

Enter Boeing (NYSE: BA) stock in a beauty contest, and it wouldn’t get many votes. But long-term investing isn’t a beauty pageant; it’s about finding good value stocks with plenty of upside potential. Boeing is a winner in that regard, even though its recent update might have been disappointing for some. Here’s why its worth

3 Dividend Stocks to Buy in November That Keep Paying

Some companies treat their dividend like a bill they have to pay every month, not a bonus they hand out when times are good. That mindset is what separates a stock that merely offers a dividend from one that has actually built its business around protecting it, through recessions, inflation spikes, and years when growth

0
Would love your thoughts, please comment.x
()
x