Much of what we know about the stock market comes from a mix of theory and empirical evidence.
For example, the idea that earnings drive stock prices is supported by the view that a business’s value is tied to how much money it makes. And decades of market data show that stock prices and earnings have exhibited a tight correlation.
There are also ideas that make intuitive sense, but the evidence supporting them is shoddy. In the stock market, this is a big problem because people will trade on these ideas, only to underperform the market.
Especially when it comes to price behavior, if a theory were both sound and reliable, we’d probably hear more about people consistently beating the market with some bulletproof trading strategy. But we don’t.
With that in mind, here are five ideas about the stock market that I’d describe as myths or misunderstandings.
Periods of strong stock market returns should be followed by periods of weak returns, and vice versa. Right?
If you take a long-term chart of the stock market and add a trendline, you’ll see prices above the line for some time and below it most of the time. This makes it tempting to say that the market exhibits mean reversion, or a tendency to gravitate back toward some historical average.
Unfortunately, this behavior is so inconsistent that Professors Paul Marsh, Mike Staunton, and Elroy Dimson concluded that “popular evidence for mean reversion is an ‘optical illusion’ that employs hindsight.” They addressed this issue in the 2025 edition of UBS’s “Global Investment Returns Yearbook” and also explored it at length in the 2013 edition, when Credit Suisse published it.
They even went so far as to compare the belief in mean reversion to the Gambler’s Fallacy, the assumption that past outcomes inform future ones.
If mean reversion in the market were consistent and predictable, then there would be a way to trade the phenomenon in such a way as to generate above-average returns. But you don’t really hear about funds or traders consistently beating the market by trading the expectation of mean reversion. (Maybe some secretive hedge fund somewhere has figured it out and they’re not telling us.)
“Market-timing strategies based on mean reversion typically gave lower, not higher, returns,” Marsh, Staunton, and Dimson found.
That’s not too surprising when you see the various stats showing periods of strong returns are often followed by more strong returns. Indeed, history shows that investing at all-time highs has produced better returns than investing on all other days.
Keep this in mind the next time someone suggests we’re “due” for weak returns because we just experienced strong returns. What just happened won’t tell you what’s coming next.
Read more about this here.
One of the most popular ways to measure value is to divide an asset’s price by its earnings. This is the price-to-earnings (P/E) ratio. When a stock’s P/E is above its historical average, it’s considered expensive. When it’s below average, it’s considered cheap.
This has led many to assume that expensive stocks tend to get cheaper and cheap stocks tend to get more expensive. In other words, valuations tend to revert to a mean, right?
“We cannot emphasize enough that valuation metrics are NOT historically mean-reverting,” Goldman Sachs analysts wrote in January. They’ve characterized it as “an oft-repeated myth.”
The firm has advanced this controversial view since 2013 (and again in 2022 and 2025). To make their point, they used a Dickey-Fuller test, a tool statisticians use to analyze time-series data. The test found that P/E ratios lacked stationarity, which means the averages aren’t stable over time.
This conclusion aligns with arguments from some top Wall Street strategists in recent years. They’ve argued that persistent improvements in business performance and capital structures have justified the higher valuations we’ve seen lately, an idea supported by theory.
And so, the mean itself is moving.
The idea that valuations aren’t mean-reverting probably makes a lot of people uncomfortable. Then again, trading based on the assumption of mean reversion hasn’t exactly yielded consistent results for people.
Read more about this here and here.
One of the main reasons to buy the stock of a single company is that you believe the price will outperform the market average over some period of time. Otherwise, you’d just put that money into an index fund tracking the market average.
A lot of people try their hand at stock picking. But most fail to beat the market.
Why? Because most stocks lag the market. And it’s far more than half.
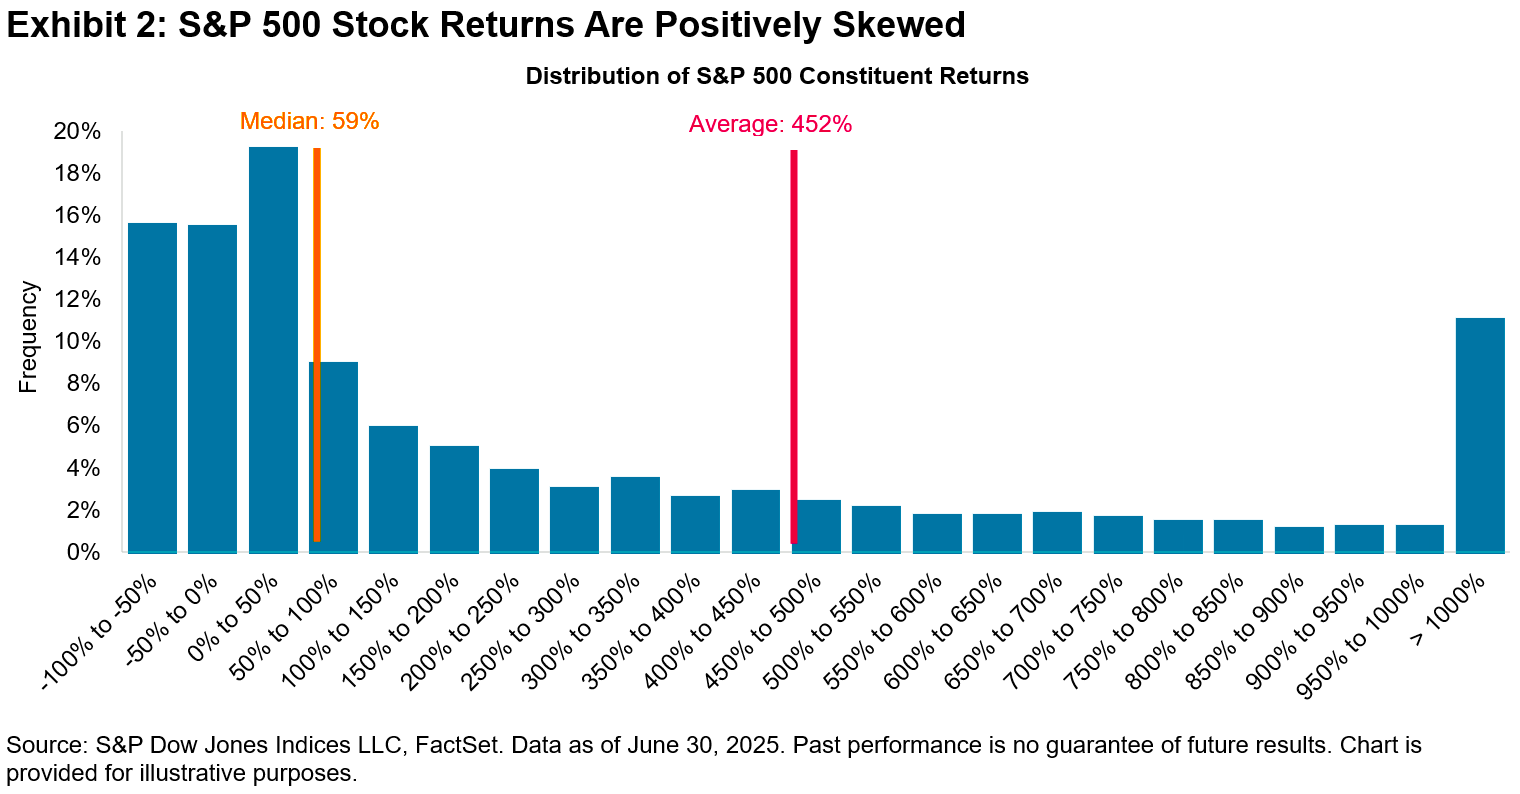
In a study published last year, S&P Dow Jones Indices analysts found that just 19% of S&P 500 companies outperformed the average stock’s return from 2001 to 2025. Most S&P stocks underperformed the index in 13 of the past 24 calendar years.
Even with stock correlations very low and dispersion high — conditions that theoretically favor those looking to beat the market — professional stock pickers have struggled to identify winners!
The truth is that market averages, which have trended higher over the years, are driven by a relatively small number of stocks that generate eye-popping returns. ASU Professor Hendrik Bessembinder has published several studies showing this. Even Warren Buffett has attributed Berkshire Hathaway’s outstanding equity portfolio performance to “a few winners.”
Read more about this here.
Let’s say you got lucky and managed to buy one of these few stocks that go on to smoke the rest of the market. Buckle up.
In a report published last year, Morgan Stanley’s Michael Mauboussin and Dan Callahan studied the price behavior of 6,500 stocks. They took a closer look at the 20 stocks with the best total shareholder returns over the 40 years from 1985 to 2024.
“The median maximum drawdown was 72% for the best group, and the median maximum drawdown duration, the time from peak to trough, was 2.9 years,” they found. “The median time to return to the prior peak was 4.3 years.”
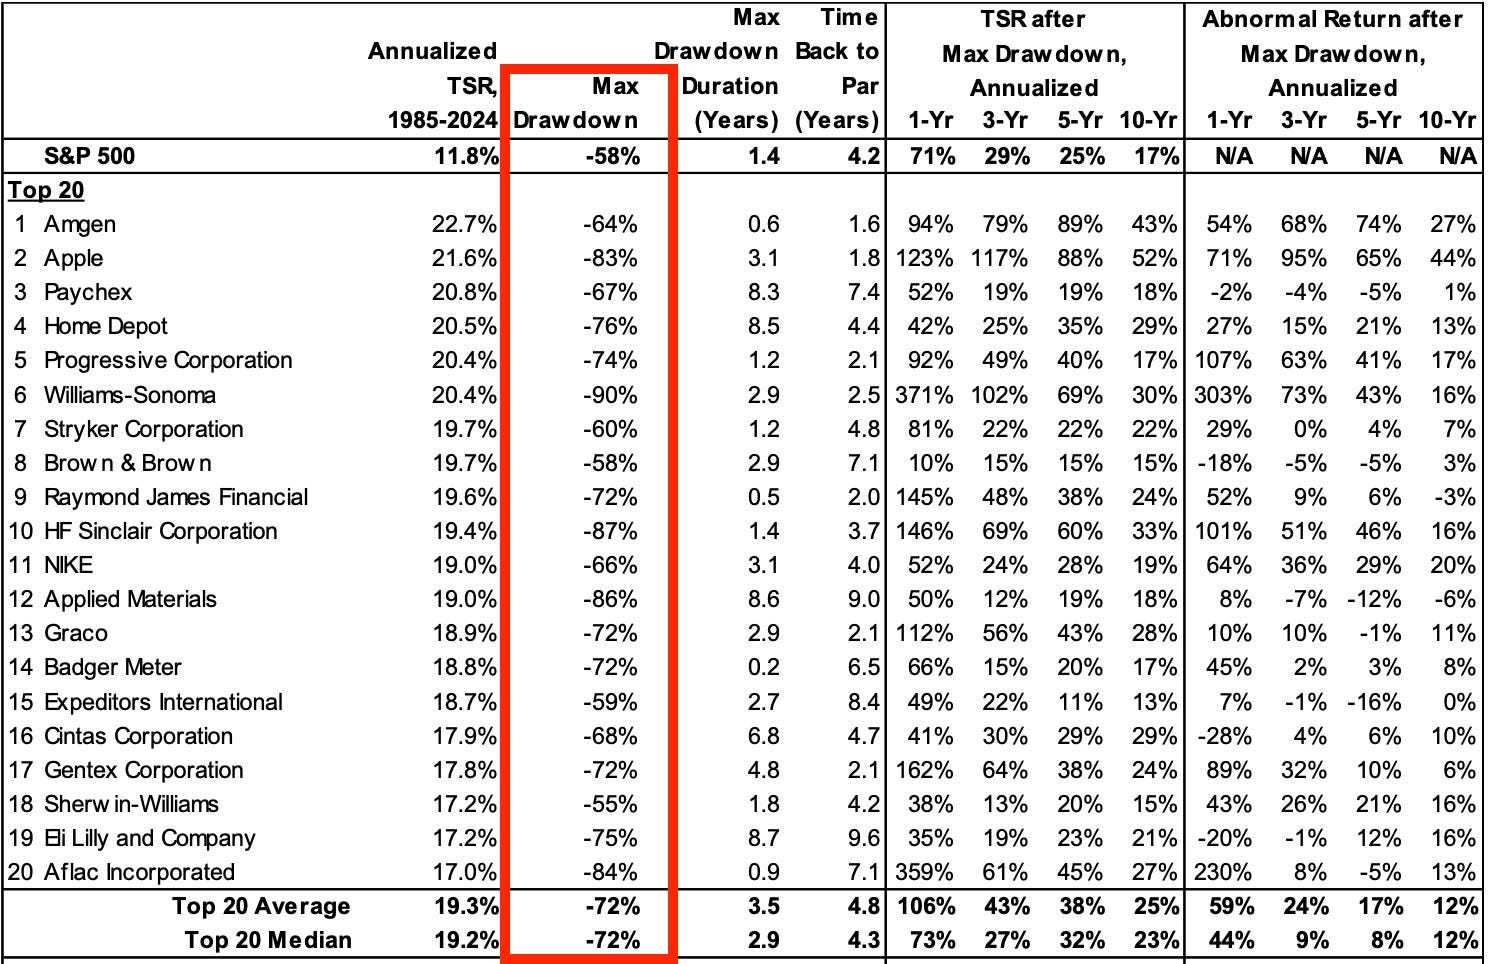
Just thinking about one of my positions losing 72% of its value makes me queasy, even knowing full well this is the average behavior of the best stocks.
If you’re a fund manager with picks like this, you may be fired long before you’ve been proven right.
Read more about this here.
The first thing many of us are taught about the stock market is that the average annual return is about 8% to 10%, give or take a point or two.
That gives many people the impression that the market climbs 8% to 10%-ish somewhat frequently.
But that’s far from the truth.
Carson Group’s Ryan Detrick ran the numbers. Since 1950, the S&P 500 returned 8%-10% in just four years.
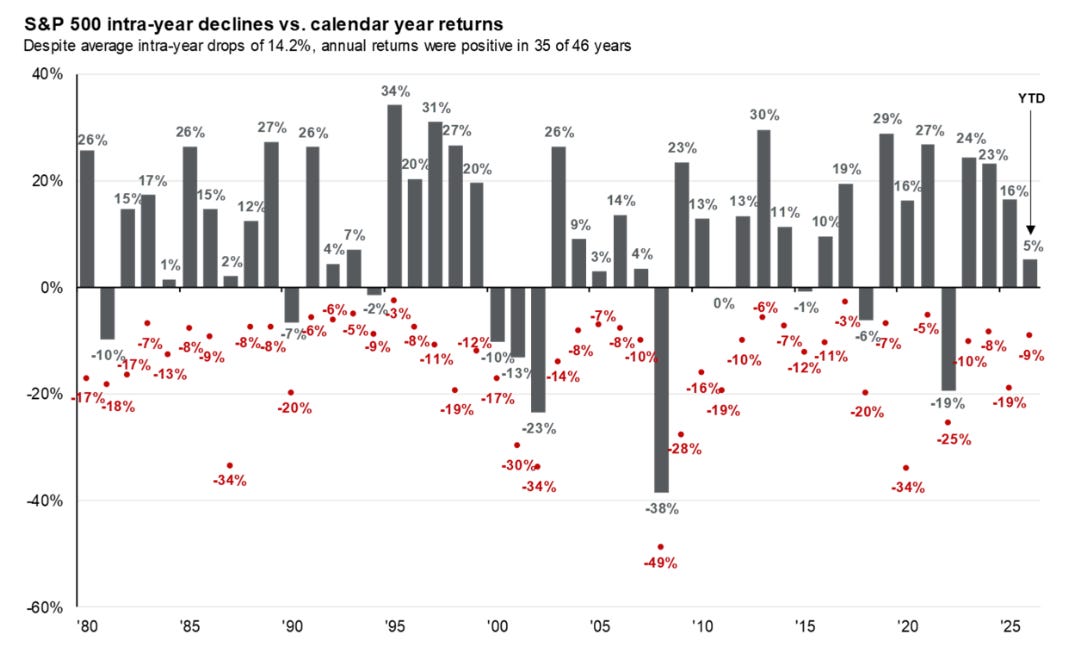
In reality, the long-term average is the result of many above-average years and many below-average years. Ritholtz Wealth Management’s Ben Carlson observed that in the average up-year, the S&P returned 21%. And in the average down-year, the index lost 13%.
Read more about this here.
Maybe you’d be ill-advised to try to beat the market by trading on one of these myths or misunderstandings.
But that doesn’t mean you should ignore them entirely.
Sometimes, weak returns follow strong returns, valuations move toward the mean, half the stocks you pick beat the market, the outperforming stocks you own never lag, and we get an average year in the market.
In other words, sometimes we do get those brief moments when the market behaves as our gut expects.
Just because the markets can be chaotic and unpredictable doesn’t mean they never make sense. It’s just that they don’t make sense on a predictable schedule.
–
Related from TKer:
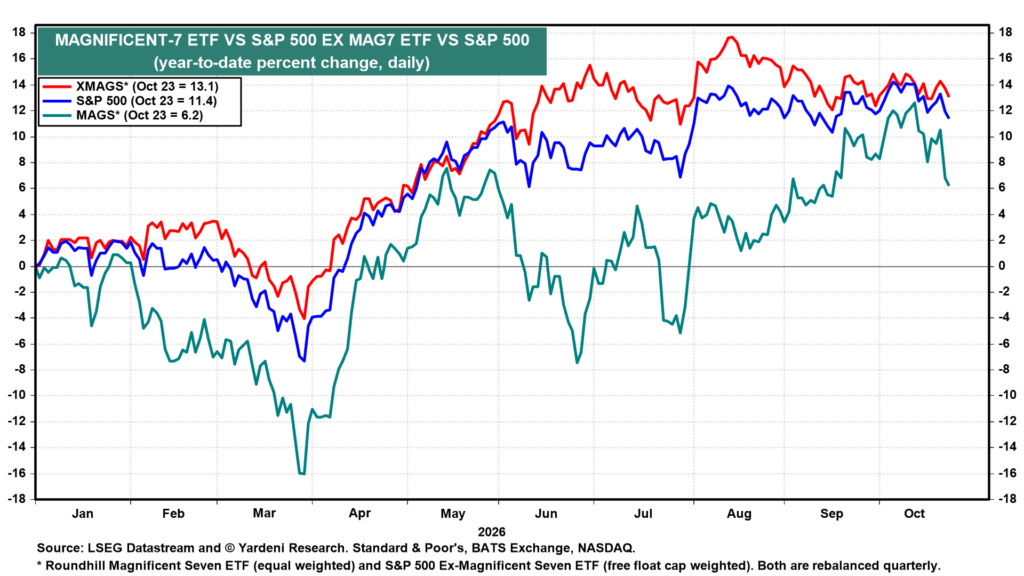
📉The stock market fell last week, with the S&P 500 shedding 0.5% to end at 7,623.68. The index is now down 2.5% from its October 6 closing high of 7,818.93 and up 11.4% year-to-date. For market insights, check out the Stock Market tab at TKer. »
There were several notable data points and macroeconomic developments since our last review:
💳 Card spending data is holding up. From BofA: “Total card spending per HH was up 4.9% y/y in the week ending Oct 17, according to BAC aggregated credit & debit card data. Relative to last week, y/y department store spending growth improved the most while entertainment saw the largest decline. Lower-income spending growth has consistently outpaced higher-income spending growth over the past several weeks.”
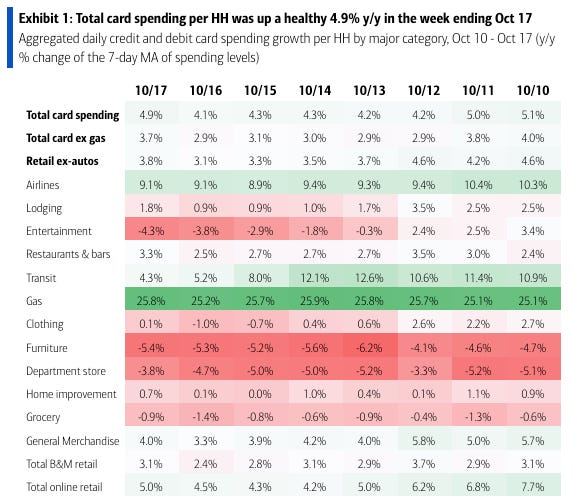
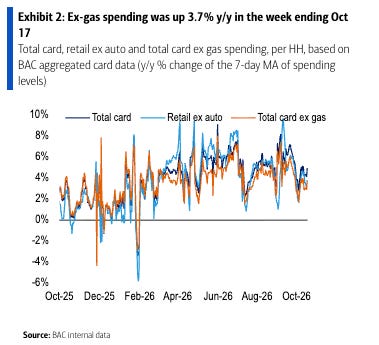
Consumer spending data has looked a lot better than consumer sentiment readings. For more on this contradiction, read: We’re taking that vacation whether we like it or not 🛫 and Household finances are both ‘worse’ and ‘good’ 🌦️
⛽️ Gas prices tick lower, but remain high. From AAA: “The national average for a gallon of regular gasoline fell 6 cents in the last week to $4.27. The drop is fueled by the transition to winter-blend gasoline which is cheaper to produce and costs less for consumers. But high crude oil prices are preventing steep declines at the pump. Currently, the price for a barrel of crude oil is nearing $100 per barrel amid instability in the Strait of Hormuz. This month is poised to set a record as the most expensive October ever for gas prices following similar records set in August and September of this year.”
Here’s a longer-term look at gas and diesel price trends, as tracked by the EIA.
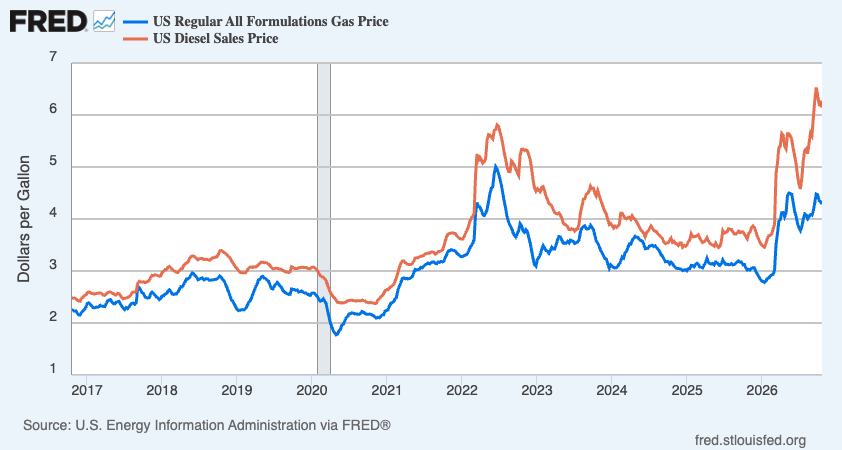
For more on energy prices, read: Our love-hate relationship with rising oil prices in charts 💔🛢️📊
👎 Consumer vibes are in the dumps. From the University of Michigan’s October Surveys of Consumers: “While year-ahead business conditions improved about 14%, they stand 16% less than last October’s read. This month’s decline in the Current Conditions subindex was driven entirely by buying conditions for durables, which plunged 18% on the basis of higher interest rates and rising concerns about the affordability of such purchases. Purchasing power continues to dominate consumer views of the economy. Sentiment is now 10% below a year ago and 15% less than February, just prior to the Iran conflict.”
For more on consumer sentiment, read: What consumers do > what consumers say 🙊
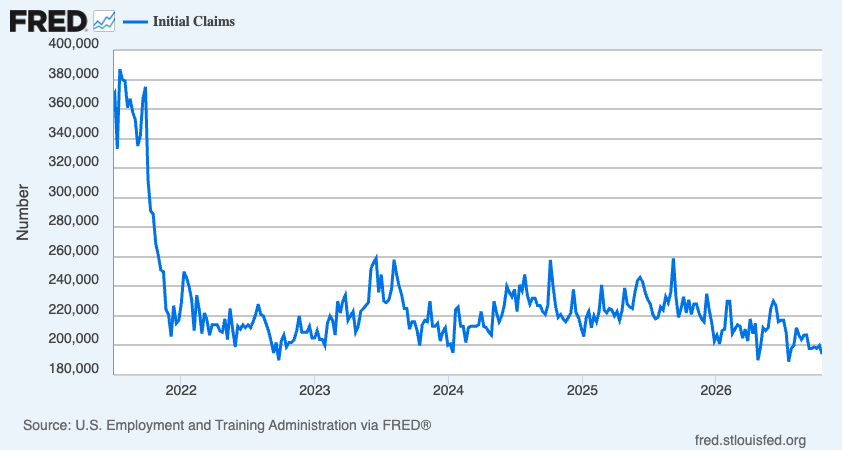
💼 New unemployment insurance claims, total ongoing claims remain low. Initial claims for unemployment benefits ticked down to 194,000 during the week ending Oct. 17, down from 200,000 the week prior. This metric remains at levels historically associated with economic growth.
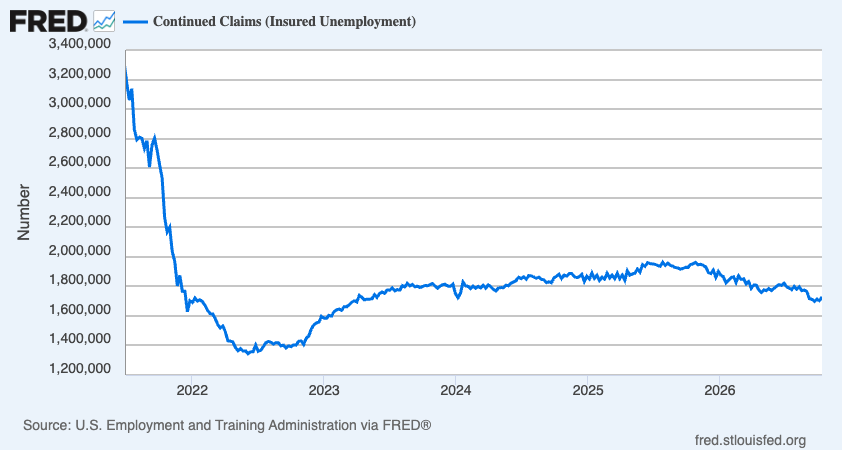
Insured unemployment, which captures those who continue to claim unemployment benefits, ticked up to 1.73 million during the week ending Oct. 10.
For more on the labor market, read: Why mass tech layoffs have little effect on total employment 💾
🤔 Recent private job growth is positive. According to payroll processor ADP, private U.S. employers added 18,500 jobs in the four weeks ending Oct. 3.
For more on the labor market, read: Things are looking up in the labor market 👍
🏠 Mortgage rates remain elevated. According to Freddie Mac, the average 30-year fixed-rate mortgage ticked down to 7.32%, down from 7.4% last week. It remains near the highest average rate since Nov. 2023.
As of Q2, there were 149.5 million housing units in the U.S., of which 87.0 million were owner-occupied and about 40% were mortgage-free. Of those carrying mortgage debt, almost all have fixed-rate mortgages, and most of those mortgages have rates that were locked in before rates surged from 2021 lows. All of this is to say: Most homeowners are not particularly sensitive to the weekly movements in home prices or mortgage rates.
For more on mortgages and home prices, read: Why home prices and rents are creating all sorts of confusion about inflation 😖
🏠 Homebuilder sentiment falls. From the NAHB: “Housing remains squeezed by supply-side constraints and significant affordability challenges. Demand persists, but higher mortgage rates, elevated construction costs and weaker consumer confidence are keeping more buyers on the sidelines. As a result, buyer traffic has fallen to its lowest level since April 2012, excluding the pandemic’s onset in April 2020.”
🔨 New home construction starts fell. Housing starts declined 5.2% in September to an annualized rate of 1.22 million units, according to the Census Bureau. Building permits fell 0.2% to an annualized rate of 1.40 million units.
It’s worth noting that the starts metric has a very large margin of error. For more on margins of error, read: Mathematical context can totally change the story 🧮
🤔 Economic activity survey signals growth cooled. From S&P Global’s October U.S. Flash PMI: “The output readings from the survey are consistent with GDP growing at a 5% annualized rate after a 4% expansion was signaled for the third quarter. Especially healthy corporate earnings and profits are also indicated, and hiring has surged as companies seek to boost capacity to fulfill stronger customer demand. If the reopening of the economy after COVID is excluded, recent months have seen the best growth spell for US businesses since early 2015. However, cost pressures remain a key concern, notably as the renewed surge in oil prices reverberates through to impact a wide variety of goods and services.”
Keep in mind that during times of perceived stress, soft survey data tends to be more exaggerated than actual hard data.
For more on this, read: What businesses do > what businesses say 🙊 and 4 sometimes-conflicting ways I’m thinking about the economy 😬😞😎🙃
🇺🇸 Most U.S. states are still growing. From the Philly Fed’s September State Coincident Indexes report: “Over the past three months, the indexes increased in 47 states, decreased in two states, and remained stable in one, for a three-month diffusion index of 90. Additionally, in the past month, the indexes increased in 38 states, decreased in seven states, and remained stable in five, for a one-month diffusion index of 62.”
📈 Near-term GDP growth estimates are tracking positively. The Atlanta Fed’s GDPNow model sees real GDP growth rising at a 3.5% rate in Q3.
For more on GDP and the economy, read: It’s too ambiguous to just say ‘the economy’ 🤦🏻♂️ and Economic data can often be both ‘worse’ and ‘good’ 🌦️
Earnings look bullish: The long-term outlook for the stock market remains favorable, bolstered by expectations for years of earnings growth. And earnings are the most important driver of stock prices.
Demand is positive: Demand for goods and services remains positive, supported by healthy consumer and business balance sheets. Personal spending activity remains at record levels. Core capex orders, which are a leading indicator of business spending, have been trending higher.
Growth rates have cooled: While the economy remains healthy, growth has normalized from much hotter levels earlier in the cycle. The economy is less “coiled” these days as major tailwinds like job openings and excess savings have faded. Job creation, while positive, is not as hot as it used to be. It has become harder to argue that growth is destiny.
Actions speak louder than words: We are in an odd period, as hard economic data has decoupled from soft, sentiment-driven data. Consumer and business sentiment has been relatively poor, even as tangible consumer and business activity continues to grow and trend at record levels. From an investor’s perspective, what matters is that the hard economic data holds up.
Stocks are not the economy: There’s a case to be made that the U.S. stock market could outperform the U.S. economy in the near term, thanks largely to positive operating leverage. Since the pandemic, companies have aggressively adjusted their cost structures. This included strategic layoffs and investment in new equipment, including AI-powered hardware. These moves are driving positive operating leverage, meaning modest sales growth — in the cooling economy — translates into robust earnings growth.
Mind the ever-present risks: We should not get complacent. There will always be risks to worry about, such as U.S. political uncertainty, geopolitical turmoil, energy price volatility, and cyberattacks. There are also the dreaded unknowns. Any of these risks can flare up and spark short-term market volatility.
Investing is never a smooth ride: Economic recessions and bear markets are harsh realities that all long-term investors should expect as they build wealth in the markets. Always keep your stock market seat belts fastened.
Think long-term: For now, there’s no reason to believe the economy and the markets will face a challenge they can’t overcome. The long game remains undefeated, and long-term investors can expect that streak to continue.
For more on how the macro story is evolving, check out the previous review of the macro crosscurrents. »
Here’s a roundup of some of TKer’s most talked-about paid and free newsletters about the stock market. All of the headlines are hyperlinked to the archived pieces.
The stock market can be intimidating: It’s real money on the line, the information is overwhelming, and people can lose fortunes very quickly. But it’s also where thoughtful investors have long accumulated wealth. The main difference between those two outlooks comes down to misconceptions about the stock market that can lead people to make poor investment decisions.
Passive investing usually means buying and holding a fund that tracks an index. And no passive investment strategy has attracted as much attention as buying an S&P 500 index fund. However, the S&P 500 — an index of 500 of the largest U.S. companies — is anything but a static set of 500 stocks.

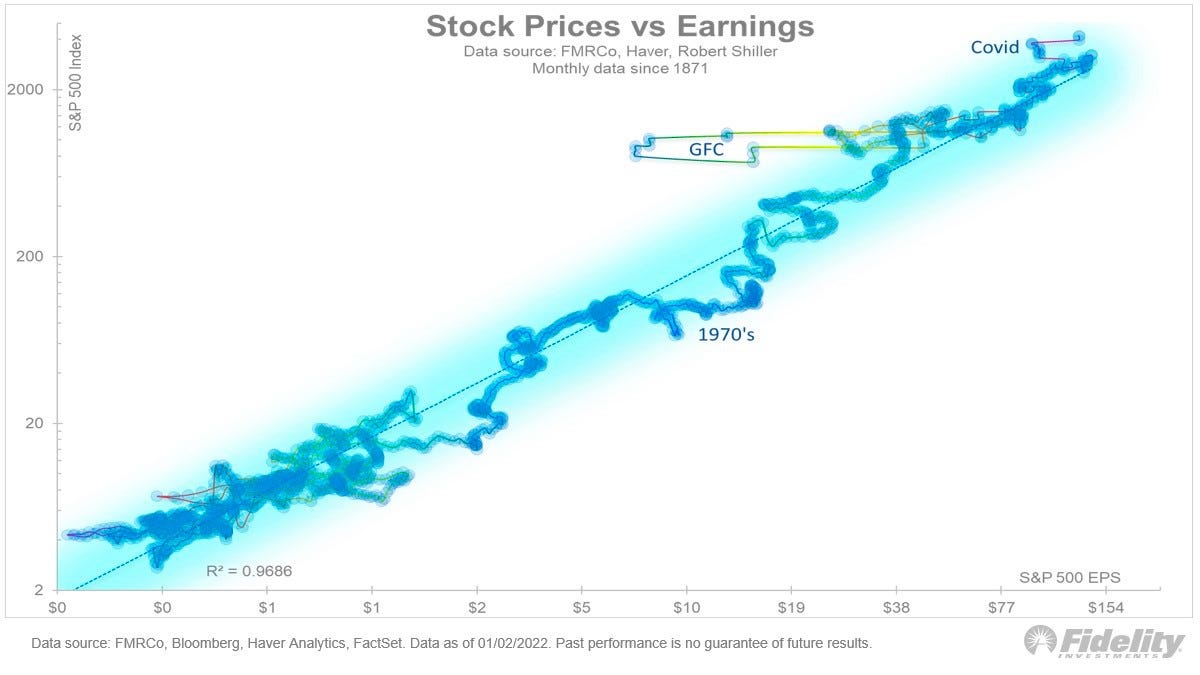
For investors, anything you can ever learn about a company matters only if it also tells you something about earnings. That’s because a stock’s long-term moves can ultimately be explained by the underlying company’s earnings, earnings expectations, and uncertainty about those expectations. Over time, stock prices and earnings have a very tight statistical relationship.
Investors should always be mentally prepared for major stock market sell-offs. It’s part of the deal when you invest in an asset class that is sensitive to the constant flow of good and bad news. Since 1950, the S&P 500 has averaged a max annual drawdown (i.e., the biggest intra-year sell-off) of 14%.
Every recession in history was different. And stock performance around them varied widely. There are two things worth noting. First, recessions have always been accompanied by a significant drawdown in stock prices. Second, the stock market bottomed and inflected upward long before recessions ended.

Since 1928, the S&P 500 has generated a positive total return in more than 89% of five-year periods. Those are pretty good odds. When you extend the timeframe to 20 years, you’ll see that the S&P 500 has never had a period where it didn’t generate a positive return.
While a strong dollar may be great news for Americans vacationing abroad and U.S. businesses importing goods from overseas, it’s a headwind for multinational U.S.-based corporations doing business in non-U.S. markets.

…you don’t want to buy them when earnings are great, because what are they doing when their earnings are great? They go out and expand capacity. Three or four years later, there’s overcapacity and they’re losing money. What about when they’re losing money? Well, then they’ve stopped building capacity. So three or four years later, capacity will have shrunk and their profit margins will be way up. So, you always have to sort of imagine the world the way it’s going to be in 18 to 24 months as opposed to now. If you buy it now, you’re buying into every single fad every single moment. Whereas if you envision the future, you’re trying to imagine how that might be reflected differently in security prices.
Some event will come out of left field, and the market will go down, or the market will go up. Volatility will occur. Markets will continue to have these ups and downs. … Basic corporate profits have grown about 8% a year historically. So, corporate profits double about every nine years. The stock market ought to double about every nine years… The next 500 points, the next 600 points — I don’t know which way they’ll go… They’ll double again in eight or nine years after that. Because profits go up 8% a year, and stocks will follow. That’s all there is to it.
Long ago, Sir Isaac Newton gave us three laws of motion, which were the work of genius. But Sir Isaac’s talents didn’t extend to investing: He lost a bundle in the South Sea Bubble, explaining later, “I can calculate the movement of the stars, but not the madness of men.” If he had not been traumatized by this loss, Sir Isaac might well have gone on to discover the Fourth Law of Motion: For investors as a whole, returns decrease as motion increases.
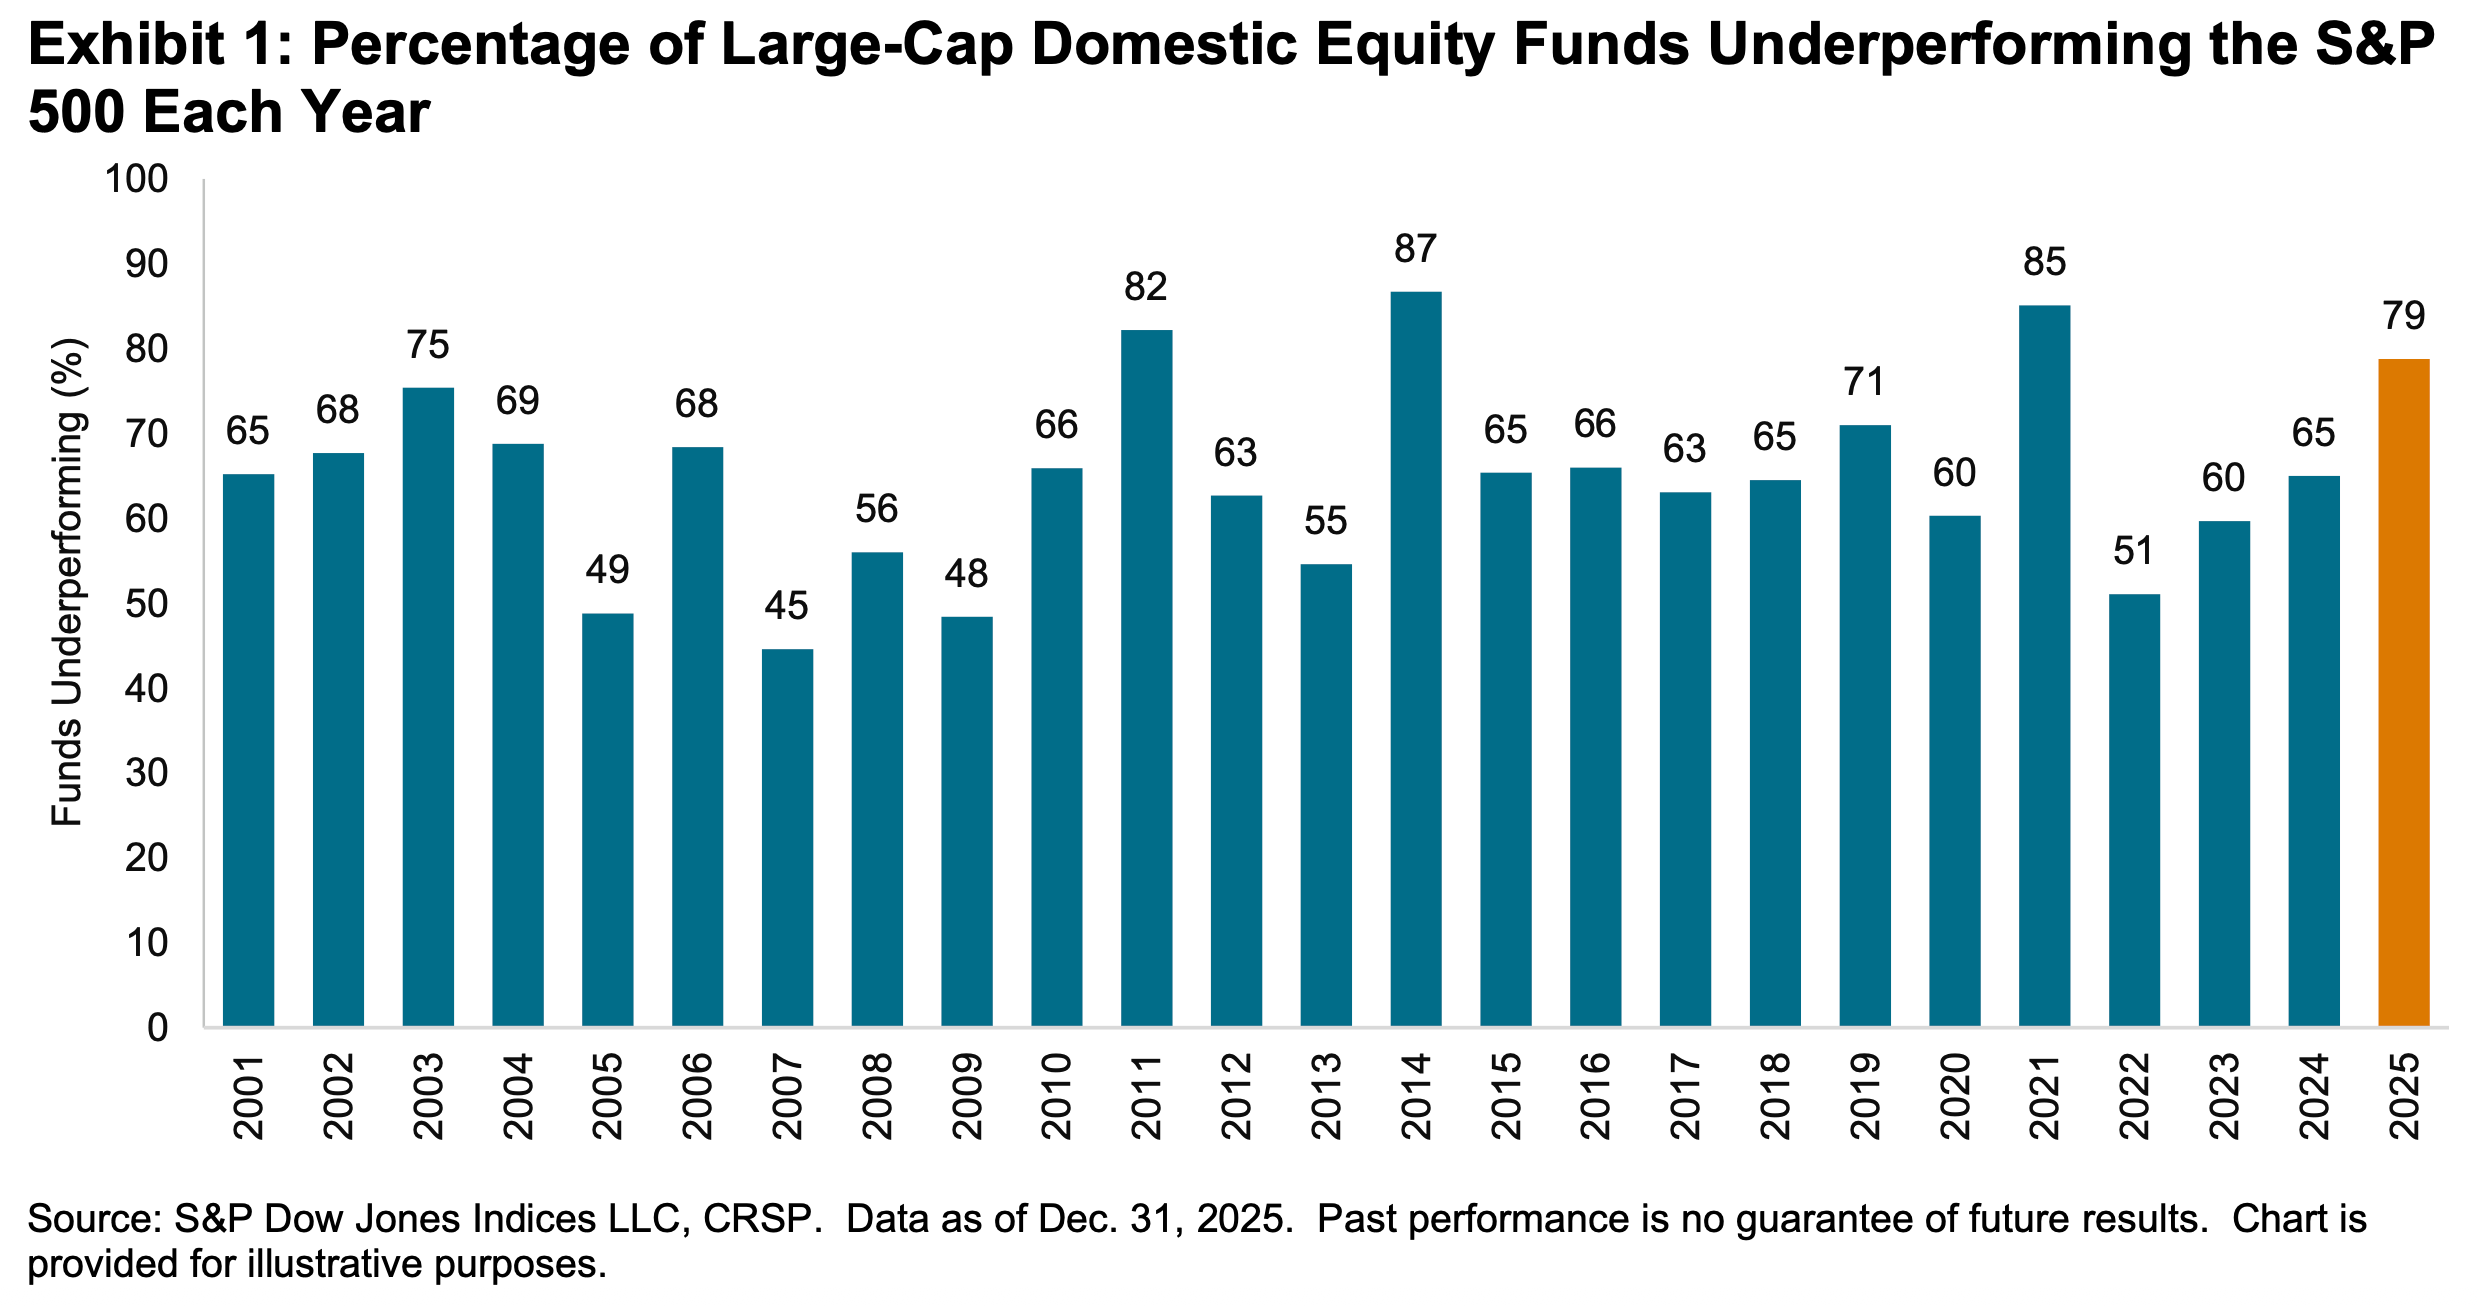
According to S&P Dow Jones Indices (SPDJI), 79% of U.S. large-cap equity fund managers underperformed the S&P 500 in 2025. As you extend the time horizon, the numbers get even worse. Over three years, 67% underperformed. Over 5 years, 89% underperformed. And over 20 years, 93% underperformed. This 2025 performance marked the 16th consecutive year the majority of fund managers in this category have lagged the index.
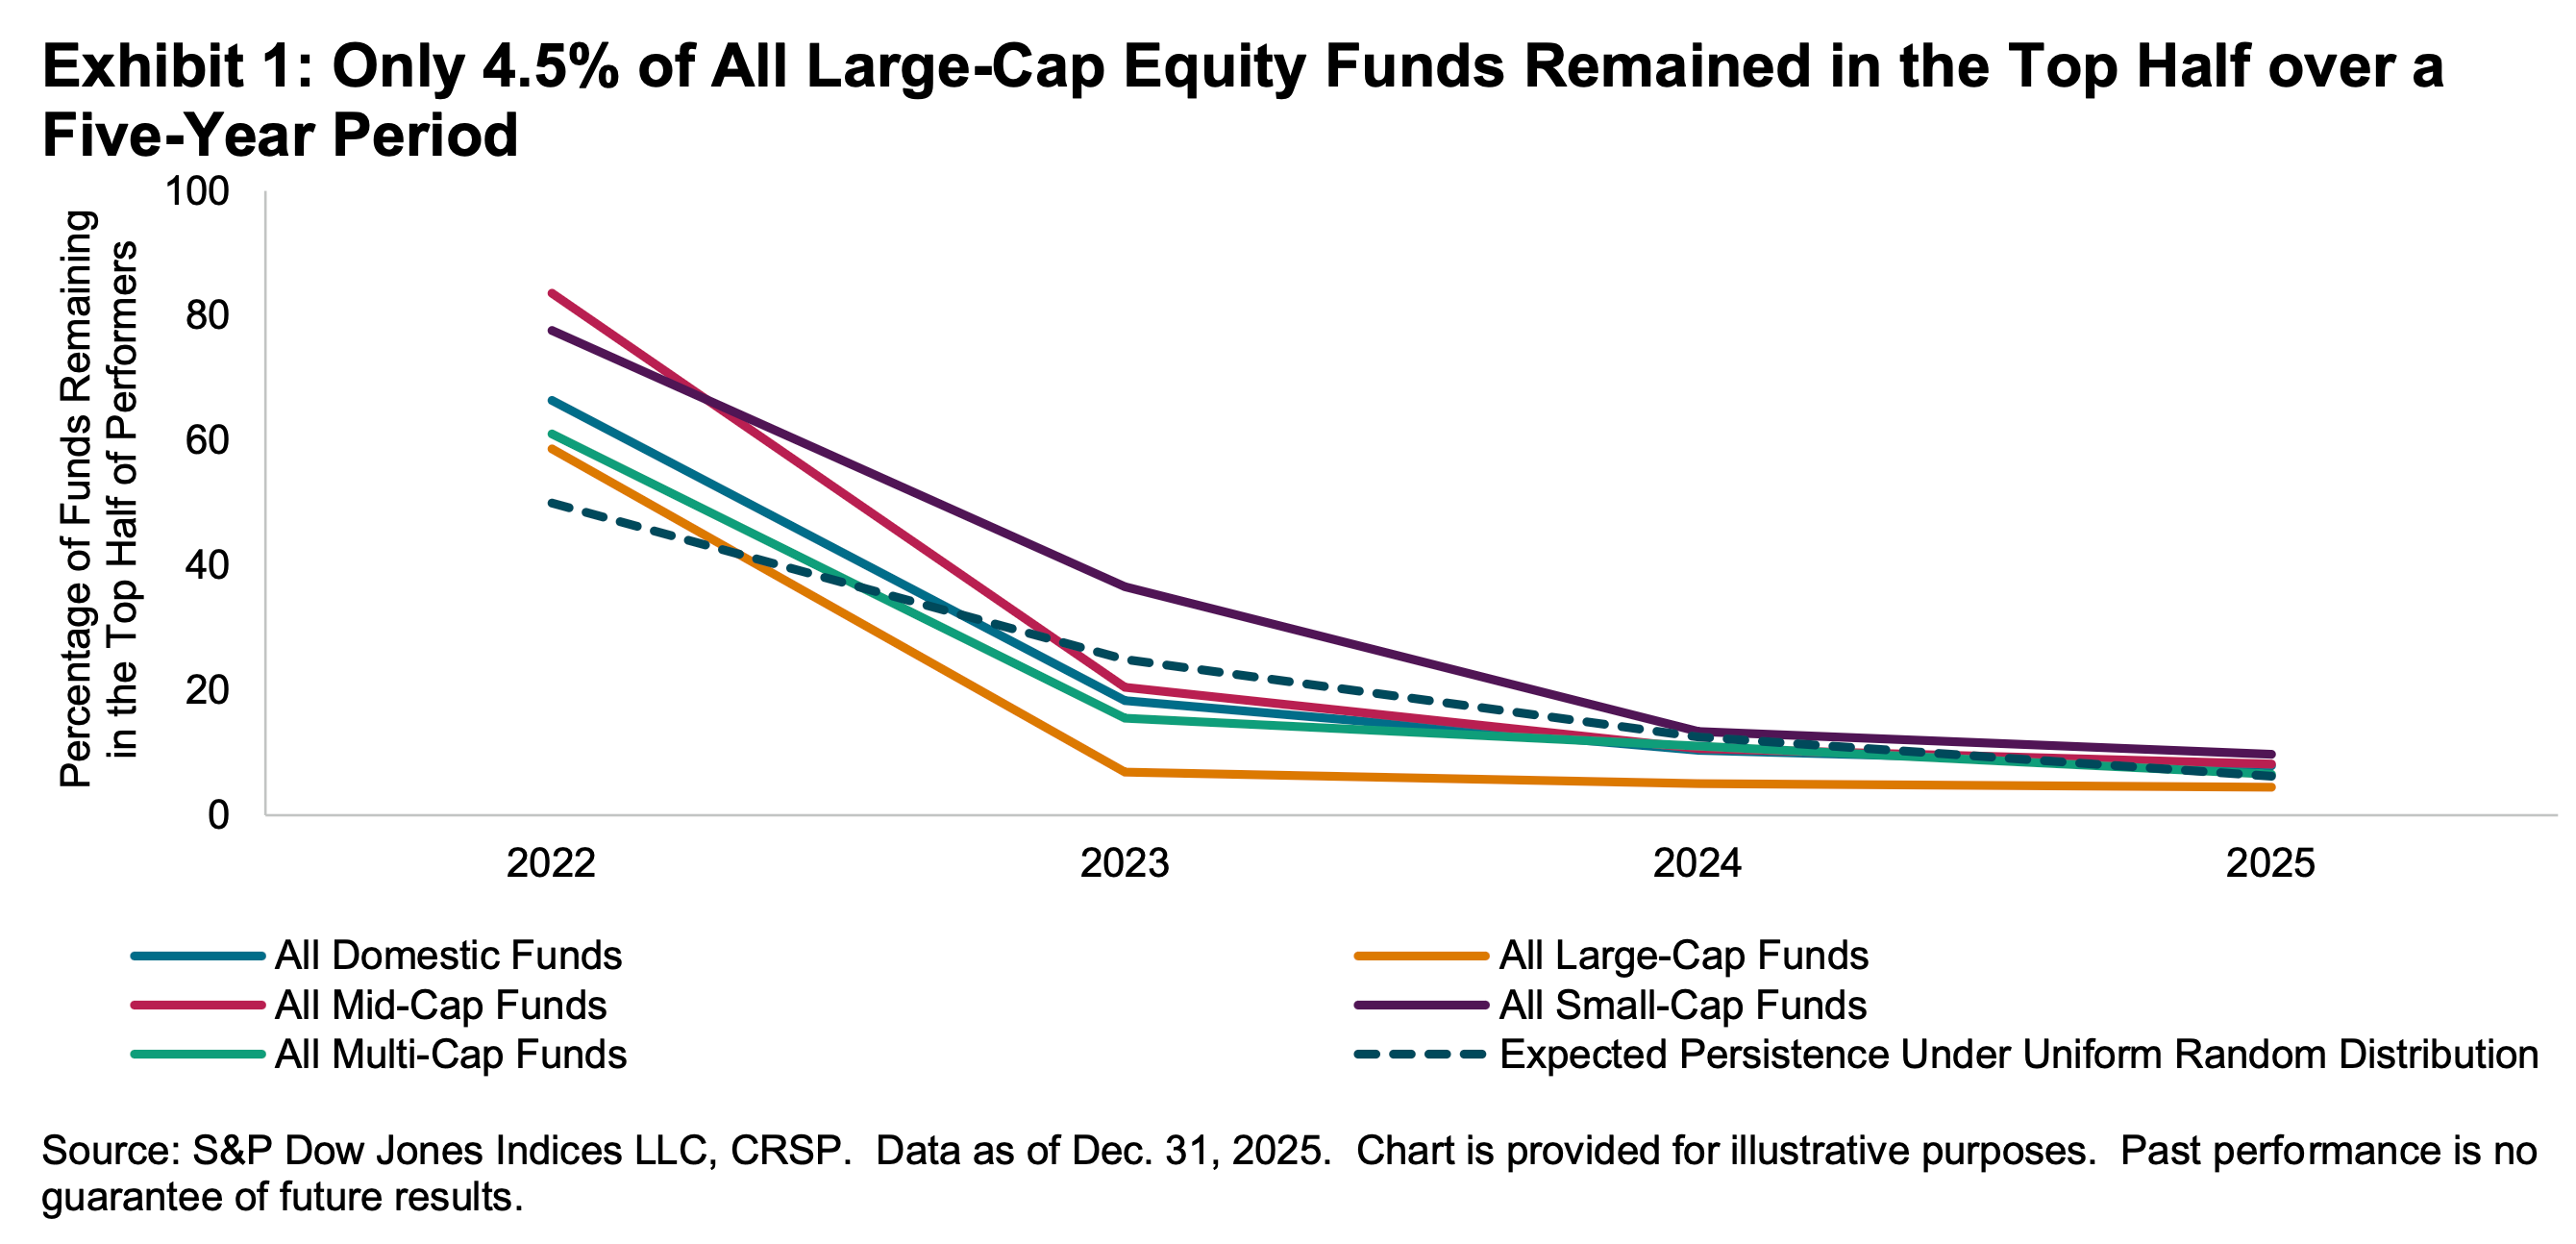
Even if you are a fund manager who generated industry-leading returns in one year, history says it’s an almost insurmountable task to stay on top consistently in subsequent years. According to S&P Dow Jones Indices, of the 334 large-cap equity funds in the top half of performance in 2021, 58.7% remained at the top half in 2022. However, just 6.9% remained on top through 2023. Only 4.5% stayed on top in the five consecutive years through 2025.
It’s much more dismal when you raise the bar. Of the 164 large-cap equity funds in the top quartile in 2021, just 20.1% remained in that category in 2022. That percentage fell to literally 0.0% in 2023.
Picking stocks in an attempt to beat market averages is an incredibly challenging and sometimes money-losing effort. Most professional stock pickers can’t do this consistently. One reason is that most stocks don’t deliver above-average returns. According to S&P Dow Jones Indices, only 19% of S&P 500 stocks outperformed the average stock return from 2001 to 2025. Over this period, the average S&P 500 stock returned 452%, while the median stock returned just 59%.