The S&P 500 has gained nearly 14.1% so far this year (as of Oct. 9). But much of the market’s earnings growth remains concentrated in major technology companies.
According to London Stock Exchange Group (LSEG), S&P 500 earnings are expected to grow around 31% year over year in the third quarter. The global financial markets data and infrastructure provider also expects technology sector and prominent artificial intelligence (AI) players such as Alphabet, Amazon, and Meta Platforms to account for roughly two-thirds of that earnings growth.
Image source: Getty Images.
While the current focus is mainly on AI companies building computing capacity and infrastructure, I expect the next phase of AI adoption will benefit businesses generating measurable productivity gains from AI.
If I had to buy one stock today to benefit from this shift through 2030, it would be Synopsys (SNPS -3.85%). The company provides the software and intellectual property (IP) used to design increasingly complex chips and engineering systems.
The market’s next winners may not build AI data centers
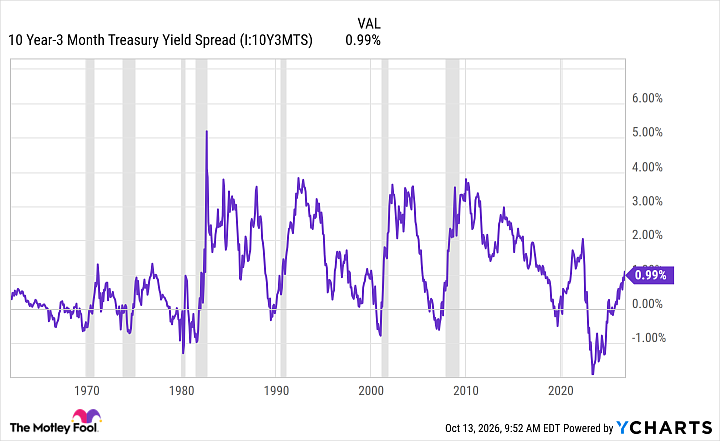
The U.S. 10-year Treasury yield reached approximately 5.24% on Oct. 9. Morgan Stanley projects that AI infrastructure will need roughly $1.5 trillion in outside funding by 2028. With interest rates remaining elevated, the challenge for companies is not just expanding computing capacity but generating enough profits to justify the enormous investment.

Today’s Change
(-3.85%) $-18.49
Current Price
$461.45
Key Data Points
Market Cap
Day’s Range
$454.49 – $472.17
52wk Range
$362.55 – $539.48
Volume
519.1K
Avg Vol
2.1M
Gross Margin
62.88%
Hence, I expect investors to increasingly reward companies that make AI computing more efficient and profitable by 2030. The demand for specialized processors, industrial automation, and AI-assisted engineering could accelerate as businesses focus on reducing costs and improving productivity.
While this trend could broaden earnings growth beyond today’s dominant AI infrastructure suppliers, established leaders such as Nvidia and Amazon could continue benefiting from growing computing demand. Synopsys, on the other hand, stands to benefit from the increasing number and complexity of chip designs as companies develop computing solutions tailored to different applications.
Synopsys could capture more value from its customers
The bigger opportunity for Synopsys lies in changing how it earns revenue. Synopsys earns licensing fees when customers use its IP in chip designs, with some agreements also generating royalties from chip sales.
In September 2026, Synopsys announced a multi-year licensing agreement worth more than $1 billion with Amazon for customized semiconductor IP for multiple generations of chips. The agreement’s licensing value excludes potential royalties, which could provide Synopsys with additional revenue as Amazon’s chip production increases.
Synopsys’ $34.9 billion acquisition of Ansys could also help it generate more revenue from existing customers. Engineers designing advanced chips must account for how heat, electrical interference, and other physical factors affect performance. Synopsys has already launched products that bring these simulations into the chip-design process. Management expects the combination of new products and cross-selling to generate $400 million in additional annualized revenue by fiscal 2029.
The company’s partnership with OpenAI could create another growth opportunity. The companies are developing a specialized model GPT-Synopsys to automate certain chip-design tasks. Synopsys’ existing tools will help verify the results. The companies also plan to share revenue from the offering. However, Synopsys still needs to prove that increased use of AI-powered tools can offset any decline in demand for traditional software licenses.
Synopsys’ ambitious 2030 financial targets
Synopsys’ reported revenue jumped 49.2% year-over-year over the first nine months of fiscal 2026. However, much of that growth came from its Ansys acquisition. Comparing revenue as if Ansys had been part of Synopsys in both years suggests growth of only about 7.4%. This is an approximate comparison, not the company’s official organic growth rate.
The company’s Design IP revenue declined 0.7% year-over-year over the first nine months of fiscal 2026. Yet, management is now targeting annual growth of at least 17% for the Design IP business from fiscal 2026 through fiscal 2030. Achieving that target would require a significant acceleration from its recent performance.
Management expects approximately $11.15 billion revenue in fiscal 2027. The company is also targeting 15% annual revenue growth from fiscal 2026 through fiscal 2030. If achieved, revenue could reach nearly $17 billion by fiscal 2030. The company’s targeted 50% non-GAAP operating margin would translate into approximately $8.5 billion in adjusted operating income in fiscal 2030.
The cash-flow projections are equally important. Synopsys expects around $3.1 billion in free cash flow in fiscal 2027. The company is also targeting annual free cash flow growth in the mid-20% range from fiscal 2026 through fiscal 2030. Assuming 25% annual growth, free cash flow could nearly double to $6.1 billion by fiscal 2030. This would imply an improvement in free cash flow margin from around 28% in fiscal 2027 to 36% in fiscal 2030. Hence, achieving these projections would require not only higher revenue but also better cash generation from each dollar of sales.
Synopsys’ valuation leaves little room for mistakes
Synopsys shares were trading at approximately 27 times projected fiscal 2027 adjusted earnings and 61 times GAAP earnings (as of Oct.9). The lower adjusted PE multiple excludes expenses such as acquisition-related amortization and stock-based compensation.
The company expects around $960 million to $980 million in stock-based compensation in fiscal 2027, or around 31% to 32% of its projected $3.1 billion in free cash flow. Issuing shares to employees could dilute existing shareholders, while repurchasing shares to offset that dilution would consume cash.
Management is also targeting annual adjusted earnings growth in the mid-20% range through fiscal 2030. Assuming 25% annual growth from the midpoint of its fiscal 2027 EPS guidance of $19.08, adjusted EPS could reach approximately $37.27 by fiscal 2030.
However, at 20 times those earnings, the stock could reach approximately $745 by fiscal 2030, representing 46% upside. A lower multiple of 15 would imply just $559, or 10% upside. These scenarios show how valuation changes could limit shareholder returns despite strong earnings growth.
Hence, I would buy a modest position in Synopsys, while paying attention to accelerating underlying revenue growth, improving Design IP profitability, and higher free cash flow per share.