I Have $250k in an IRA and Will Receive $3,000 Monthly From Social Security. Can I Retire in 5 Years at 70?


If you’re in your mid-60s and still working, it may be time to start seriously planning for retirement. That doesn’t mean you need to leave work immediately, but retirement is likely on the horizon.

Imagine you’re 65 years old, you have $250,000 in an IRA and expect to receive $3,000 per month from Social Security. Can you retire at age 70? Depending on your personal circumstances and risk tolerance, This could be enough money to generate some financial security, although much of your flexibility would depend on how you manage the IRA for the next five years.

If you need additional help planning for retirement, consider speaking with a financial advisor.

How To Plan For Retirement In 5 Years
A 65-year-old man who plans to retire at age 70 looks over the investments in his IRA.

If you plan to retire in five years and have $250,000 in your portfolio, how you manage your IRA will go a long way to determining what kind of retirement you can expect. Five years isn’t a lot of time, but it’s still enough time for some significant growth. Consider these three hypothetical scenarios:

Investing in Bonds

Currently, investment-grade bonds are paying an average 5.6% yield. If you invest your whole IRA into bonds right now, you could expect to retire with about $328,291. Since bonds issue a rate of return backed by the credit of the underlying institution, your odds of volatility or loss are low.

Invest in the S&P 500

Investing all of your assets in an S&P 500 index fund could produce higher returns than bonds, but it’s a riskier option. But based on the market’s approximate average rate of return (10%), putting everything into the stock market could potentially leave you with $402,628 by age 70. And if you had lots of time for the market’s fluctuations to even out, this might be an excellent plan. But five years is likely too short of a window to justify investing 100% in equities.

Build a 60/40 Portfio

Conventional wisdom is to split your assets into a mix of stocks and bonds. By your 60s, this is often either a return-heavy portfolio of 60% stocks and 40% bonds or a safety-heavy portfolio of 20% stocks and 80% bonds. Historically, a 60/40 portfolio has grown at around 8.77% per year, according to Vanguard. While past performance doesn’t guarantee future results, if we assume your IRA grows at 8.77% per year over the next five years, it would be worth about $380,615 by age 70.

None of these strategies will transform your financial situation, but a strategic mix of stocks and bonds could provide you with a combination of growth and safety. A financial advisor can potentially help you find an asset allocation aligned with your risk tolerance and goals.

Income and Withdrawals

Next, you’ll want to assess what your income needs will be in retirement.

If you retire at 70, you will max out your potential Social Security benefits. While Social Security won’t be enough on its own, $3,000 per month in benefits is a good start.

Then, you’ll need to determine how much you can withdraw from your IRA. This is more complicated. The two issues here are:

  • Investments going into retirement
  • Investments while in retirement

Basically, how do you plan to invest your IRA in the five years before retirement, and, as a result, how much money will you have in your portfolio at age 70?

Then, once you do retire, how will you continue investing? What kind of growth can you expect during retirement?

While we don’t have enough space to explore all possible options, let’s assume you use the 60/40 split over the next five years. This would leave you with $380,615 in your IRA by the time you retire.

If you keep your 60/40 asset allocation in place throughout retirement, you could potentially afford to withdraw about $2,000 per month after taxes at age 70. You could then increase your withdrawals for inflation in each subsequent year and stretch your IRA for nearly 25 years. Just remember, these figures assume your portfolio would continue to average 8.77% per year.

When combining your Social Security benefits and IRA withdrawals, you’d have a total retirement income of around $5,000 per month in year 1. However, this approach would leave you exposed to market volatility, as 60% of your portfolio would still be invested in equities. Keep in mind that you may want to rebalance your portfolio as you get older, shifting a larger percentage of your assets into bonds.

As you can see, building an income plan for retirement can be complicated, but a financial advisor can help. If you’re looking for a fiduciary advisor, this tool can help you match with one.

Bottom Line
A retired couple relax on a park bench.

Can you afford to retire at age 70 with $250,000 in an IRA and $3,000 in monthly Social Security income? It depends on several factors, but the most important are how you invest in this portfolio and how much you need to live on. It’s possible that these assets could produce $5,000 in your first year of retirement and keep pace with inflation thereafter.

Retirement Planning Tips

  • As you can see, Social Security can play a major role in your retirement income plan. SmartAsset’s Social Security calculator can help you estimate how much your benefits may be depending on when you plan to claim them.
  • A financial advisor can help you build a comprehensive retirement plan. Finding a financial advisor doesn’t have to be hard. SmartAsset’s free tool matches you with up to three vetted financial advisors who serve your area, and you can have a free introductory call with your advisor matches to decide which one you feel is right for you. If you’re ready to find an advisor who can help you achieve your financial goals, get started now.

Photo credit: ©iStock.com/SDI Productions, ©iStock.com/Space_Cat, ©iStock.com/pixdeluxe

The post I Have $250k in an IRA and Will Receive $3,000 Monthly From Social Security. Can I Retire in 5 Years at 70? appeared first on SmartReads by SmartAsset.

The views and opinions expressed herein are the views and opinions of the author and do not necessarily reflect those of Nasdaq, Inc.
Source link

Visited 4 times, 1 visit(s) today

Related Article

Prediction: $150 a Month Invested in Micron Stock Will Be Worth This Much by Year-End 2030

Over the last year, memory chip manufacturers have benefited from extraordinary demand for artificial intelligence (AI). In particular, Micron Technology (NASDAQ: MU) has witnessed its market capitalization propel from just $53 billion at the start of the AI revolution to more than $1 trillion today. MU Market Cap data by YCharts Missed Nvidia in 2009?

Micron Tripled in 2026. Can It Repeat in 2027?

Micron (NASDAQ: MU) stock has more than tripled so far in 2026, making it the fourth-best-performing stock in the S&P 500 (SNPINDEX: ^GSPC) this year. That’s an impressive run, but for investors, the past really doesn’t matter; only the future. So, could Micron repeat this feat in 2027? One metric suggests that the answer to

GM Just Beat Earnings Estimates. Is Ford Still the Better Dividend Stock?

Quick Read Ford (F) yields nearly 5% versus GM’s (GM) sub-1%, making Ford the clear winner for investors who need cash income today. GM’s dividend is covered 18 times by free cash flow versus Ford’s 2.6 times, making GM’s payout far safer for long-term holders. GM’s stock gained 187% over ten years versus Ford’s 62%,

Trumpflation Is Evolving, and There’s a New Twist That Threatens to Sink Stocks

For the better part of the last four years, the stock market has been unstoppable. The artificial intelligence (AI) infrastructure build-out has helped propel the Dow Jones Industrial Average (DJINDICES:^DJI), S&P 500 (SNPINDEX:^GSPC), and Nasdaq Composite (NASDAQINDEX:^IXIC) to several record highs this year. But these gains may prove fleeting, courtesy of Trumpflation — inflation specifically

Old Republic International Earnings: What To Look For From ORI

Old Republic International Earnings: What To Look For From ORI Insurance conglomerate Old Republic International (NYSE:ORI) will be reporting earnings this Thursday before market open. Here’s what investors should know. Old Republic International missed analysts’ revenue expectations last quarter, reporting revenues of $2.33 billion, up 5.2% year on year. It was a softer quarter for

Cathie Wood’s Ark Invest Grew Its Portfolio to $15.4 Billion Last Quarter, With Tesla, AMD, and a New SpaceX Stake Making Up About 18% of ARKK Assets. Is Her Concentrated Bet Paying Off?

Cathie Wood is one of America’s most-watched tech investors, known for her extreme bullishness on Bitcoin and disruptive future technologies like robotics and artificial intelligence (AI). According to her company’s most recent 13F SEC filing, as of the second quarter, Cathie Wood’s Ark Invest portfolio had a total of $15.4 billion of assets under management.

Inflation Is Back. Is A Stock Market Crash Next?

The S&P 500 has gained 12.3% this year. That’s with oil above $100 a barrel, consumer prices climbing 3.7% a year and a 10-year Treasury yielding 5.1%. Stocks are behaving as though none of that counts. So could inflation knock the index down 40%? Can anyone call the market’s next move, whether that’s tomorrow, next

Advice for home sellers: ‘If you’re trying to time the market, you can’t’

Homeowners waiting for a better moment to sell should stop trying to time the market, National Association of Home Builders CEO Jim Tobin said. “If you’re trying to time the market, you can’t do it,” Tobin told Yahoo Finance on Monday. “If you talk to anybody who’s bragged about when they sold their home or

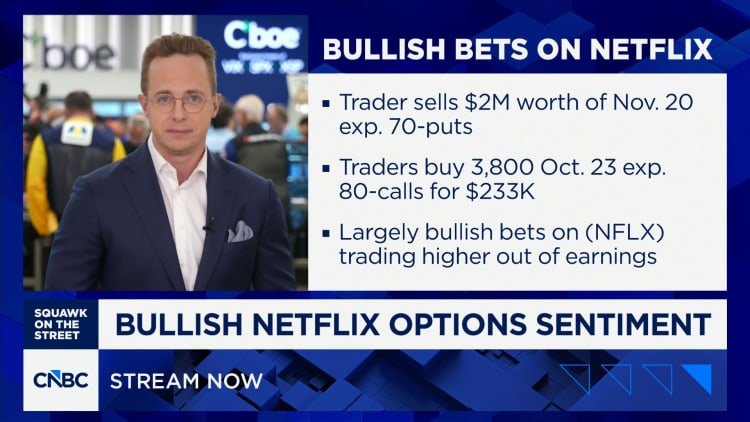
Traders are betting Netflix’s stock drama may be coming to an end

A slumping stock price. C-suit shakeups. Corporate layoffs. A failed takeover bid. It’s not a new drama on Netflix, but rather the drama that has surrounded the streaming giant as it limps into earnings with its stock nearly off 50% from its all time highs. Option traders are betting the drama might be coming to

CEO Elon Musk Just Gave SpaceX Investors Great News

Space Exploration Technologies Corp. (NASDAQ:SPCX) reported its third-quarter earnings after the market closed on Oct. 20, with results that largely topped Wall Street estimates. Here are the key numbers: Missed AI’s “Act 1”? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But

2 Dividend Stocks Crushing the Market in 2026 (and Which Ones Can Keep Going)

Broader equities have been fairly resilient this year. However, there remains a very real possibility that macroeconomic problems and geopolitical tensions will eventually lead to a market crash. One way to prepare for that is to invest in dividend stocks with strong underlying businesses. Here are two options investors should consider: Johnson & Johnson (NYSE:

Meta Q3 earnings to test Wall Street’s stomach for AI spending

Meta (META) will kick off Big Tech’s earnings season when it reports its third quarter results after the bell on Wednesday. For the third quarter, Meta is expected to post earnings per share of $3.56 on revenue of $63.3 billion, according to Bloomberg analyst consensus estimates. That’s up from the $1.05 and $51.2 billion the

Prediction: Oct. 21 Will Be a Huge Day for the Stock Market

Artificial intelligence (AI) stocks have led this bull market over the past three years, pushing the S&P 500 to record highs. Investors were eager to get in on this promising technology early on, and in many cases, they’ve already greatly benefited. For example, chip designers such as Nvidia and Advanced Micro Devices, as well as

US Stock Market Today: S&P 500 Futures Climb On Strong Factory And Earnings Hopes

The Morning Bull – US Market Morning Update Tuesday, Oct, 20 2026 US stocks are set for a firmer open, with sentiment leaning risk on as investors focus on a clear upswing in American factory activity. The key driver this morning is stronger than expected industrial and capacity data. Industrial production rose 0.7% month over

0
Would love your thoughts, please comment.x
()
x