California Resources (CRC) Stock Still Looks Cheap Despite Market Caution

California Resources has rewarded long term holders over the past five years, which naturally puts a spotlight on whether the current share price really lines up with what its sales can support. After a period that includes both a sizeable reported loss and new clean power ambitions, the question is how much revenue strength the market is now pricing into the stock.

  • Over the past 5 years the share price has gained 30.2%. This raises the stakes on whether the present valuation is still grounded in the underlying sales base.

  • The recent US$315 million loss tied largely to hedging and the new Bloom Energy partnership can reshape expectations for future revenue mix and capital needs. This feeds directly into how investors think about what each dollar of sales should be worth today.

  • There is a second opinion on California Resources worth weighing. See what analysts think California Resources’s shares could be worth.

The issue now is whether California Resources’ current market value is justified by its sales when set against that track record and recent developments.

If this earnings story has you rethinking how much you pay for each dollar of top line, a focused screen of 34 high quality undervalued stocks is a useful next stop in your research.

Is California Resources Still Cheap on Sales?

P/S fits California Resources because current earnings are distorted by the recent US$315 million loss, while sales still give a cleaner yardstick. On this measure the stock trades on a P/S of 1.2x, which is below both the oil and gas industry average of 2.1x and the peer group at 2.5x. Compared with the tailored fair multiple the model suggests for CRC, the current P/S also screens on the low side, which indicates that the market is pricing each dollar of revenue more conservatively than those benchmarks.

Because the loss was driven largely by hedging, the discount on the P/S ratio indicates investors are still treating California Resources with some caution despite the Bloom Energy clean power partnership. For you, that gap raises the question of whether the hedging setback and new capital demands fully justify this lower sales multiple or whether sentiment has pushed it below what the firm’s revenue base alone would suggest. Explore the numbers behind California Resources’s P/S valuation.

NYSE:CRC P/S Ratio as at Nov 2026

The California Resources Narrative: What Would Justify Today’s Price?

Simply Wall St Narratives pick up where the California Resources valuation puzzle leaves off. They spell out which assumptions on future growth, margins and earnings would need to line up for the stock to be priced meaningfully higher or lower than it is today. Each one treats fair value as a thesis about the business that can be revisited over time rather than a static chart. These sit on Simply Wall St’s Community page.
One of the top community narratives on California Resources: 31% undervalued

“Cost discipline backed by ahead of schedule merger synergies and broader structural savings, including more than US$100 million of annualized reductions…”

Discover why this Narrative puts California Resources at 31% undervalued.

One more California Resources check that belongs beside the valuation work

Price and sales only tell part of the story. Separate forensic checks on California Resources have flagged potential concerns that careful investors may want to weigh before deciding what comes next. Take a closer look at 1 warning sign before settling on a valuation.

This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.

Companies discussed in this article include CRC.

Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com

Source link

Visited 1 times, 1 visit(s) today

Related Article

Taiwan’s AI Stock Boom Is Making Early-Stage Startups a Tougher Pitch

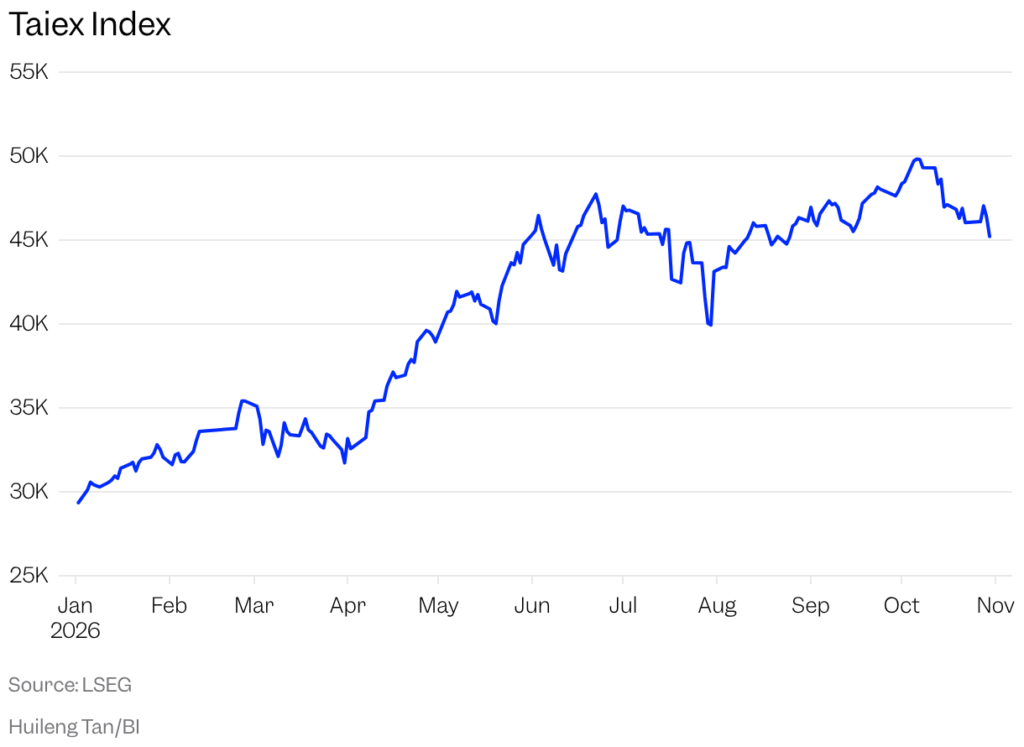
Taiwan’s AI stock boom is creating more ways for investors to profit from its chip supply chain, making early-stage startups a tougher pitch. Taiwan’s benchmark Taiex index is up more than 50% this year, making it the world’s best-performing major index after pulling ahead of South Korea’s Kospi. The gains extend well beyond Taiwan Semiconductor

MGM Q3 deep dive: margin recovery and digital growth offset soft leisure demand

MGM Q3 deep dive: margin recovery and digital growth offset soft leisure demand Hospitality and casino entertainment company MGM Resorts (NYSE:MGM) met Wall Street’s revenue expectations in Q3 2026, but sales were flat year on year at $4.21 billion. Its non-GAAP loss of $0.11 per share was significantly below analysts’ consensus estimates. Is now the

Why Amplitude Stock Jumped 23% in October

Shares of Amplitude (NASDAQ:AMPL) were among the winners last month as the data analytics software stock benefited from a broader rotation out of AI infrastructure stocks into undervalued stocks like Amplitude, and it also got a number of positive analyst notes during the month. Though there was no major company-specific news out on Amplitude, those

Options traders are getting anxious on Palantir and Apple ahead of earnings

It’s not just the neoclouds and hyperscalers that investors are anxious about.  Options data show a surge in bearish trading in anticipation of both Palantir and Apple earnings Monday afternoon. The two stocks have been on trajectories that are distinct from the broader AI trade – with Apple, in particular, trading almost inversely to the

Oracle stock slides as it borrows another $10 billion for AI spending

Five days after Oracle (ORCL) promised to rein in its fundraising, it raised the full $20 billion in a single day. Oracle kicked off a $10 billion bond sale Monday and, at the same time, filed to sell $10 billion of stock. Together, that’s every dollar of new debt and stock it said at last

Talent Infinity Completes Cancellation of Stock Options

Vancouver, British Columbia–(Newsfile Corp. – November 2, 2026) – Talent Infinity Resource Developments Inc. (CSE: TICO) (OTCQB: TIRDF) (FSE: ON8) (the “Company” or “TICO“) announces that it has completed the cancellation of stock options described in its news release dated October 14, 2026. Further to its news release dated October 14, 2026, issued at the

Stock Market to Be Jolted by Apple Earnings, Midterms, Jobs Report This Week

Buckle up for another wild week in markets. Investors are still coming off a roller coaster ride that included a painful sell-off in the AI trade on Friday, but the volatility isn’t expected to die down soon, and a handful of potential catalysts is lies ahead for investors. This week’s docket includes more Big Tech

Forget Anthropic, This Is the Best AI Investment to Buy and Hold

The highly anticipated Anthropic IPO could be one of the largest in history, with an expected valuation of between $1.5 billion and $2 billion. The Anthropic hype train, however, was knocked off the tracks a bit when the company filed its registration documents on Oct. 26. While Anthropic posted strong revenue growth in the first

Itochu Repurchases 46.2 Billion Yen of Treasury Stock in October

Market Closed – 01:30:00 2026-11-02 am EST 5-day change 1st Jan Change 2,271.00 JPY -2.39% -1.30% +14.99% Published on 11/02/2026 at 01:57 am EST MT Newswires This article is reserved for our members. Log in to continue Log inCreate an account 01:57am Itochu Repurchases 46.2 Billion Yen of Treasury Stock in October MT Oct. 30

Apple Earnings, Midterms, Jobs Data Put Markets To The Test: 3 Charts To Watch This Week

Investors will be watching Apple’s margins for whether the company can absorb higher memory-chip costs. Big Tech’s AI spending is squeezing cash flow, pushing companies toward more borrowing and stock sales. Friday’s jobs report will help determine whether slowing hiring changes expectations for another Federal Reserve rate hike in December. Apple (AAPL) earnings on Monday,

Why investors are dumping tech stocks, in one image

Tech stocks aren’t getting shredded for any old reason. It’s actually very fundamental: Free cash flow is drying up for Big Tech leaders, and capex is rising dramatically. Investors are questioning whether this ratio is totally out of whack, given more realistic growth projections for AI. The combined capex of Amazon, Alphabet, Meta and Microsoft

Marvell Plunges 13% on Lumentum Takeover Rumors: Make Your 3-5 Year Bet Right Now

Quick Read Marvell fell 14% in a week on Lumentum takeover reports, and with Lumentum’s $76 billion market cap, any deal would be a heavy lift. Marvell surged 132% year to date versus the S&P 500’s 11% gain but dropped 26% last month, leaving shares well below their $330 52-week high. Marvell’s $341 consensus target

Prediction: Nvidia Will Have an Incredible November Thanks to 1 Event

Nvidia (NASDAQ: NVDA) has been a market-average stock this year, rising about 15.5% versus 13% for the S&P 500. Investors are used to huge outperformance, and this year hasn’t delivered that. However, I believe it could be coming in November. Nvidia reports Q3 earnings in November, likely around Nov. 18, if past earnings dates are

0
Would love your thoughts, please comment.x
()
x