AppLovin has experienced sustained upward momentum driven by strong institutional accumulation and growing confidence in the company’s artificial intelligence-powered advertising infrastructure. A primary catalyst behind the stock’s appreciation is the continued commercial validation of its Axon 2.0 recommendation engine. The platform has demonstrated exceptional efficiency in audience targeting and ad delivery, which has expanded the company’s reach beyond its core mobile gaming roots and accelerated its penetration into the broader web advertising and direct-to-consumer e-commerce verticals.
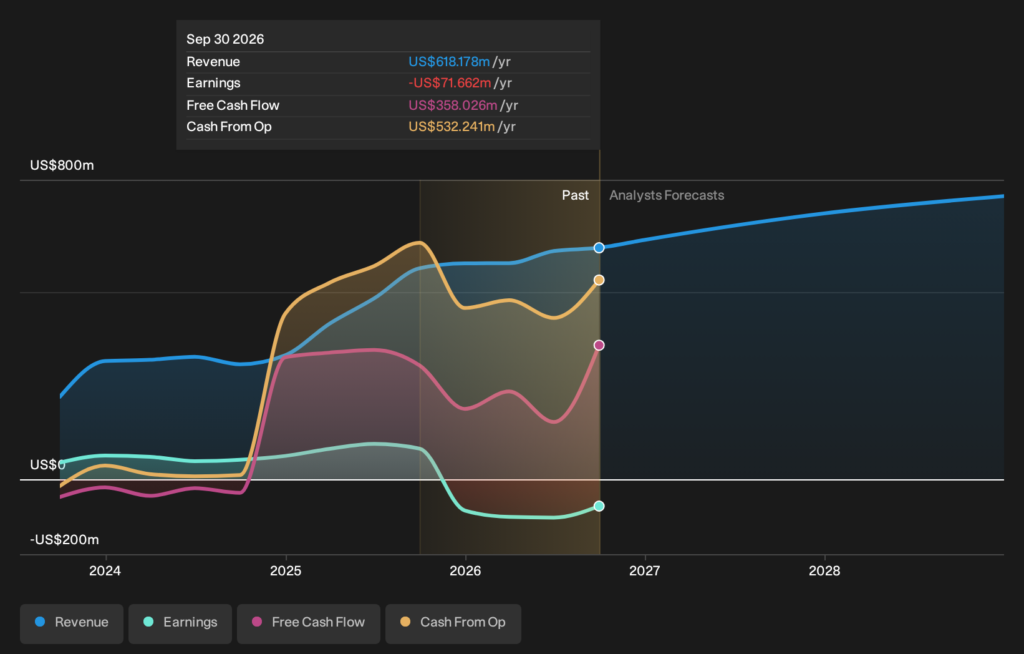
Following the recent release of its quarterly financial results, market sentiment has remained exceptionally bullish. AppLovin has delivered top-line revenue growth and expanding adjusted EBITDA margins that underscore the high operating leverage inherent in its Software Platform business. The aggressive expansion of its software segment, paired with substantial free cash flow generation, has enabled management to sustain an aggressive share repurchase program, effectively reducing the net share count and enhancing shareholder value.
Sell-side sentiment has also served as a powerful tailwind. A flurry of positive revisions from Wall Street investment banks has elevated consensus price targets, with analysts frequently citing AppLovin’s expanding total addressable market in e-commerce performance marketing as a structural growth driver. Furthermore, institutional portfolio managers have increasingly repositioned into the name to capture market-leading exposure to software-driven digital advertising, particularly as broader macroeconomic data continues to support resilient consumer spending and robust enterprise ad budgets.
From an industry perspective, digital advertising dynamics have increasingly favored platforms capable of delivering provable return on ad spend in privacy-restricted operating environments. AppLovin’s first-party data architecture and machine learning algorithms have created a formidable competitive moat, positioning the company as an attractive alternative to traditional walled gardens. This technical advantage has prompted advertisers to allocate larger testing and ongoing budgets to its ecosystem.
While the stock’s structural trajectory remains compelling, institutional investors continue to monitor potential valuation friction and execution risks tied to scaling the e-commerce vertical against well-capitalized tech incumbents. Nonetheless, the prevailing convergence of accelerating software revenue, positive earnings revisions, and institutional buying continues to support the stock’s current upward trajectory.
Technically, Applovin Corp (APP) shows a MACD (12,26,9) value of 33.745, indicating a buy signal. The RSI at 72.616 suggests buy condition and the Williams %R at 2.229 suggests overbought condition. Please monitor closely.
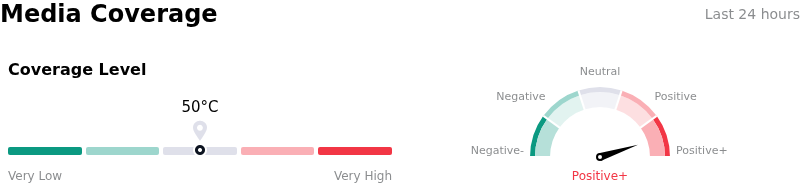
In terms of media coverage, Applovin Corp (APP) shows a coverage score of 50, indicating a moderate level of media attention. The overall market sentiment index is currently in extremely bullish zone.
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $0.00, a high of $0.00, and a low of $0.00.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.