Key highlights
- AHLL Diagnostics revenue rose 24% year on year to Rs 226.9 crore in Q2 FY27.
- AHLL Diagnostics EBITDA margin increased to 16% in Q2 FY27 from 12% in Q2 FY26.
- Average daily Diagnostics footfalls rose 15% year on year to 28,154 in Q2 FY27.
- AHLL Diagnostics had more than 2,802 collection centres as of September 30, 2026, up 21% year on year.
powered by IRIS
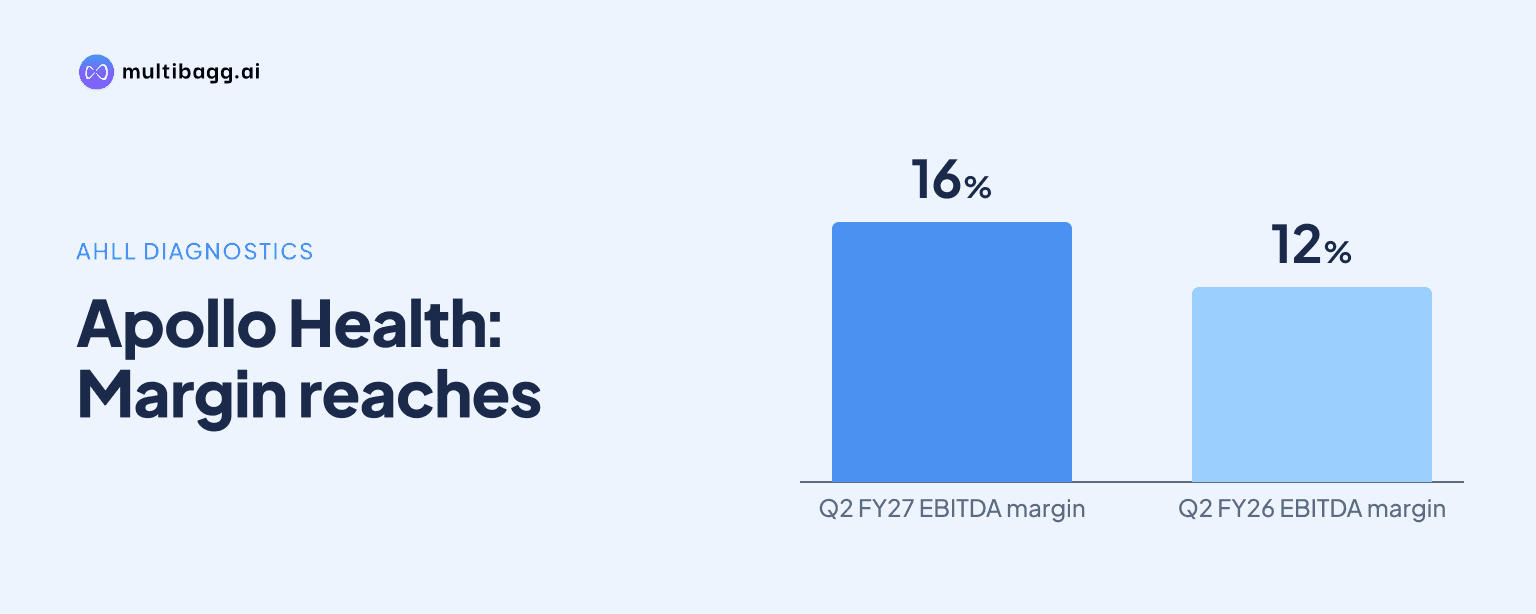
Apollo Health & Lifestyle Ltd raised its Diagnostics earnings before interest, tax, depreciation and amortisation (EBITDA) margin to 16% in Q2 FY27 from 12% a year earlier, as Diagnostics revenue increased 24% to Rs 226.9 crore and average daily external-business footfalls rose 15% to 28,154.
Know Apollo Hospitals Enterprise inside out
Results, valuation, peers and who’s buying, in one view.
How did AHLL Diagnostics perform in Q2 FY27?
AHLL Diagnostics reported revenue of Rs 226.9 crore and EBITDA of Rs 36 crore in Q2 FY27, up 24% and 64%, respectively, from Q2 FY26. EBITDA margin rose by 4 percentage points to 16%, compared with 12% in the previous-year quarter. The broader AHLL business reported revenue of Rs 429.4 crore, EBITDA of Rs 61.5 crore and a 14% EBITDA margin during the quarter.
The quarter-on-quarter figures also show an increase from Q1 FY27. Diagnostics revenue rose from Rs 200.3 crore in Q1 FY27 to Rs 226.9 crore in Q2 FY27, while EBITDA increased from Rs 28.1 crore to Rs 36 crore. The margin improved from 14% in Q1 FY27 to 16% in Q2 FY27, after having been 14% in Q4 FY26 and 10.8% in Q3 FY26.
AHLL’s H1 FY27 Diagnostics results followed the quarterly trend. Revenue increased 27% year on year to Rs 427.2 crore, EBITDA rose 89% to Rs 64 crore, and margin expanded to 15% from 10% in H1 FY26. The Q2 margin was therefore 1 percentage point above the H1 FY27 margin.
What drove AHLL Diagnostics revenue growth?
AHLL Diagnostics’ disclosed operating measures show higher patient traffic and a modest rise in realization in Q2 FY27. Average daily footfalls for outpatient and external business reached 28,154, up 15% from 24,535 in Q2 FY26. Average gross realization per patient rose to Rs 810 from Rs 733 over the same period.
The increase was also visible sequentially. Average daily footfalls rose from 24,778 in Q1 FY27 and 23,908 in Q4 FY26 to 28,154 in Q2 FY27. Average gross realization per patient increased from Rs 808 in Q1 FY27 to Rs 810, following Rs 787 in Q4 FY26. These operating measures accompanied the Rs 26.6 crore quarter-on-quarter increase in Diagnostics revenue.
AHLL also identified wellness and specialty testing as growth categories during H1 FY27. The wellness segment grew about 32% year on year and accounted for about 22% of Diagnostics revenue. The specialty segment grew about 39% year on year, while AHLL added about 28 specialty tests to its portfolio in the first half.
How much did AHLL Diagnostics expand its network?
AHLL Diagnostics had 120 laboratories, more than 2,802 collection centres and more than 4,470 pick-up points as of September 30, 2026. The business had a presence in more than 473 cities. Collection centres increased by 491 from 2,311 in Q2 FY26, which represented 21% year-on-year growth.
The collection-centre network rose through each reported period after Q2 FY26. The count moved from 2,347 in Q3 FY26 to 2,387 in Q4 FY26, then to 2,575 in Q1 FY27 and 2,802 in Q2 FY27. AHLL separately reported net additions of five laboratories and 416 collection centres during H1 FY27.
The difference between the 120 laboratories and the more than 2,802 collection centres indicates that sample access is supported by a larger collection network. Pick-up points numbered more than 4,470 as of September 30, 2026. AHLL did not disclose profitability by city, laboratory or collection centre, so the presentation does not establish the earnings contribution of individual locations.
Got a follow-up? Ask IRIS
How did AHLL Diagnostics compare with other AHLL businesses?
AHLL Diagnostics was the largest reported operating segment by revenue and EBITDA in Q2 FY27. Its revenue of Rs 226.9 crore exceeded Primary Care’s Rs 138.7 crore and Specialty Care’s Rs 84.1 crore. Diagnostics EBITDA of Rs 36 crore was also higher than Primary Care’s Rs 30.5 crore and Specialty Care’s Rs 13.3 crore.
Diagnostics recorded the fastest revenue and EBITDA growth among AHLL’s three reported operating segments. Its revenue grew 24%, ahead of Primary Care’s 12% and Specialty Care’s 15%, while its EBITDA grew 64%, compared with 48% for Primary Care and 11% for Specialty Care. Primary Care had the highest segment EBITDA margin at 22%, compared with 16% for Diagnostics and 16% for Specialty Care.
At the AHLL level, Q2 FY27 revenue increased 20% year on year to Rs 429.4 crore and EBITDA rose 79% to Rs 61.5 crore. Corporate and intra-group EBITDA costs were Rs 18.3 crore, compared with Rs 20.2 crore in Q2 FY26. AHLL said its overall revenue and EBITDA growth was primarily driven by the 24% year-on-year increase in Diagnostics revenue.
AHLL reported profit after tax of Rs 18 crore in Q2 FY27, compared with a loss of Rs 8.8 crore in Q2 FY26. AHLL completed the transfer of its stakes in ASPL and AFCPL to Kids Clinic India Limited on October 12, 2026. These businesses were classified as discontinuing operations under Indian Accounting Standard 105, with comparative financials re-presented accordingly.
What do the H1 FY27 segment results show?
AHLL Diagnostics remained the largest reported operating segment in H1 FY27, generating revenue of Rs 427.2 crore and EBITDA of Rs 64 crore. Primary Care reported Rs 265.2 crore of revenue and Rs 55 crore of EBITDA, while Specialty Care reported Rs 164.5 crore of revenue and Rs 25.7 crore of EBITDA.
Diagnostics also led H1 FY27 growth, with revenue rising 27% and EBITDA increasing 89% from H1 FY26. Primary Care revenue and EBITDA rose 12% and 37%, respectively, while Specialty Care revenue increased 7% and EBITDA rose 2%. AHLL’s total H1 revenue grew 19% to Rs 817.2 crore and EBITDA rose 83% to Rs 105.6 crore.
The H1 comparison shows a margin change across the operating segments. Diagnostics margin expanded to 15% from 10%, while Primary Care margin rose to 21% from 17%. Specialty Care margin was unchanged at 16%, making Diagnostics the segment with the largest reported H1 margin improvement.
Conclusion
AHLL’s Q2 FY27 Diagnostics performance combined a 24% increase in revenue, a 64% rise in EBITDA and a 4-percentage-point margin expansion to 16%. Higher daily footfalls, gross realization of Rs 810 per patient, a 21% increase in collection centres and growth in wellness and specialty testing were the disclosed operating measures alongside the financial improvement.
The next disclosed operating actions include AHLL’s plan to launch a few owned Primary Care clinics by the end of FY27 and planned renovations at multiple Spectra centres in upcoming quarters. For Diagnostics, the reported measures to watch are further laboratory and collection-centre additions, along with the continuation of wellness-segment growth, specialty-test additions and patient-footfall growth.
Frequently Asked Questions
AHLL Diagnostics reported EBITDA of Rs 36 crore in Q2 FY27. This was 64% higher than Rs 22 crore in Q2 FY26, and the segment’s EBITDA margin increased to 16% from 12%.
AHLL Diagnostics revenue increased 24% year on year to Rs 226.9 crore in Q2 FY27. It had reported revenue of Rs 182.7 crore in Q2 FY26 and Rs 200.3 crore in Q1 FY27.
AHLL Diagnostics had more than 2,802 collection centres as of September 30, 2026. That was 491 more than the 2,311 centres reported in Q2 FY26, alongside 120 laboratories and more than 4,470 pick-up points.
AHLL Diagnostics recorded average daily footfalls of 28,154 in Q2 FY27 for outpatient and external business. Average gross realization per patient was Rs 810, compared with Rs 733 in Q2 FY26 and Rs 808 in Q1 FY27.
AHLL Diagnostics was the fastest-growing reported operating segment in Q2 FY27 by both revenue and EBITDA. Its revenue grew 24% and EBITDA rose 64%, compared with Primary Care’s 12% and 48% and Specialty Care’s 15% and 11%, respectively.