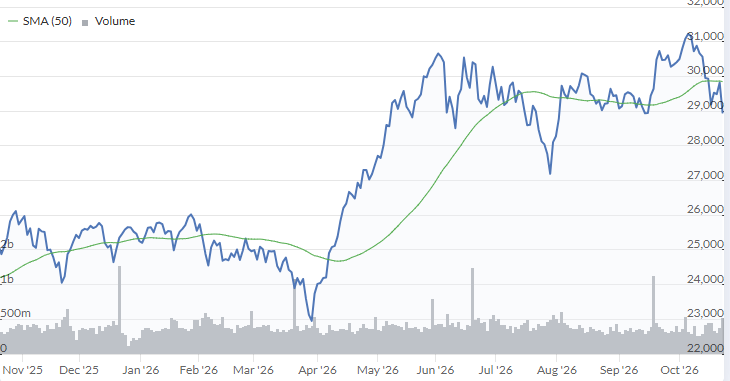
Barclays just dropped Q3 2026 numbers into a market that has been marking the stock down for weeks. The shares closed at £4.09 on 22 October, with the price sliding over the past month and quarter even as trailing earnings supported a P/E of 7.8x. That gap between weak sentiment and solid profitability is the story. Quarterly net income reached £2,387m and basic earnings per share came in at £0.13, yet the valuation still reflects caution rather than confidence. Today is less about the headline print and more about whether that emotional discount is justified.
Like the earnings power at Barclays but uneasy about buying into a stock the market is still pricing with a heavy sentiment discount? Take a look at our 7 high quality undervalued stocks to compare this setup against other companies where profitability and cautious pricing intersect.
Q3 2026 Earnings Summary
-
Total Revenue (Q3 2026 vs Q3 2025): £6,862m vs £6,535m (up 5.0%)
-
Net Income (Excl. Extra Items) (Q3 2026 vs Q3 2025): £2,387m vs £1,457m (up 63.8%)
-
Basic EPS (Q3 2026 vs Q3 2025): £0.128 vs £0.104 (up 23.7%)
-
Net Profit Margin (Trailing 12 Months vs Prior Year): 24.7% vs 22.9% (up 1.8 percentage points)
A third year of ~20% EPS growth and another buyback. Ask Charlie what makes Barclays so confident on 2026 RoTE.

Barclays’ 2026 Upside Case Meets First Real Tests
Optimists argue Barclays can turn technology spend and cost cuts into structurally higher profitability.
“The main thing that has to go right is that Barclays converts its planned technology and AI investment and structural cost actions into the targeted low 50s group cost income ratio, while managing higher loan loss guidance, staff relations, and legal disputes without eroding returns.”
The latest quarter shows partial progress. Group cost/income is 57% year to date and 62% in Q3, still above the low 50s goal but moving in that direction. Management has quantified more than £1.1b annual efficiency savings for 2027 and laid out headcount cuts of about 5,000, while reiterating 2026 RoTE and income targets, so the operational milestones that support the optimistic narrative are starting to appear in hard numbers, not just plans.
The price and this Narrative do not agree. → Uncover what this Narrative says Barclays is actually worth.
Barclays bears focus on risks that are not yet clearing
Bearish views centre on the idea that rising legal headaches could quietly cap how far Barclays can push returns.
“Despite efforts to pivot the Investment Bank toward more stable, capital efficient financing and corporate income, the legal dispute around the failure of Market Financial Solutions and associated reputational risk create a possibility of higher conduct charges or cautious client activity that could drag on fee income and profit contribution.”